Royal Mail faces further downside risk
17th March 2015 10:46
by Lee Wild from interactive investor
A fortnight ago, Credit Suisse warned that shares were overvalued given growing competition, deteriorating free cash flow story and political risk ahead of the general election in May. Now it is the turn of fellow Swiss broker UBS to stick the knife in and predict a lurch lower.
The House of Commons BIS Select Committee report on the UK mail market, published on 4 March, concluded that the Universal Service (US) is not under immediate threat, although Ofcom should have greater powers to respond rapidly if the situation changes. The Committee decided that US was a benefit, not a burden for Royal Mail.
But UBS has taken a very thick red pen to forecasts, largely due to foreign exchange risk, higher pension costs due to low interest rates, heavy investment required, and the outlook for revenues (both letters and parcel).
EPS forecasts for 2015 are little changed at 29.9p compared with consensus estimates of 32.7p. But next year, the broker's expectations, which had been in line with consensus at 31.2p, are slashed by 23% to just 24.1p. For 2017 they are cut by 19% to 26.1p.
"Although we note that cashflow is less impacted (pension change is non-cash), we believe there is less visibility and more risk to RMG forecasts than for its peers," said UBS analyst Dominic Edridge.
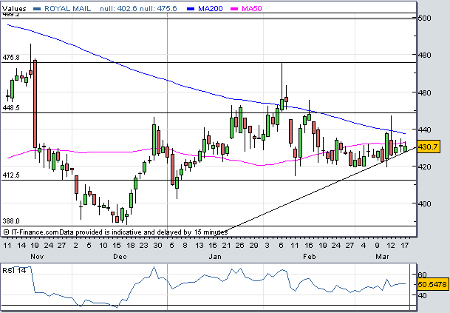
"Although RMG has announced a staff restructuring and believes it can keep underlying costs flat, it appears this is only enough to offset the top line pressure partially. We continue to believe that in the long-run RMG has to become more efficient and it remains difficult to see how that can happen under the parameters of the current labour framework (i.e., no compulsory redundancies, no change to a mainly full-time workforce)."
UBS retains its 'neutral' rating on the shares, but drops the price target from 438p to just 414p based on a discounted cash flow (DCF) of the business plus estimated surplus property valuation. It would have been more severe but for the downgrades being partly non-cash (pensions), plus the fact that the bulk of the value lies in the terminal value (i.e., sensitive to the margin assumption) and property (estimated at £536 million).
At 432p, Royal Mail shares trade on 17.9 times UBS's EPS forecasts for 2016, dropping to 16.6 times the year after, a premium to peers. There is, however, a prospective dividend yield of 4.6% and the shares have received support in recent days.
This article is for information and discussion purposes only and does not form a recommendation to invest or otherwise. The value of an investment may fall. The investments referred to in this article may not be suitable for all investors, and if in doubt, an investor should seek advice from a qualified investment adviser.