ii view: Smith & Nephew still seeks deal as guidance cut
Offering products from knee and hip replacements to wound care management. Analyst Keith Bowman assesses prospects.
4th November 2026 11:56
by Keith Bowman from interactive investor
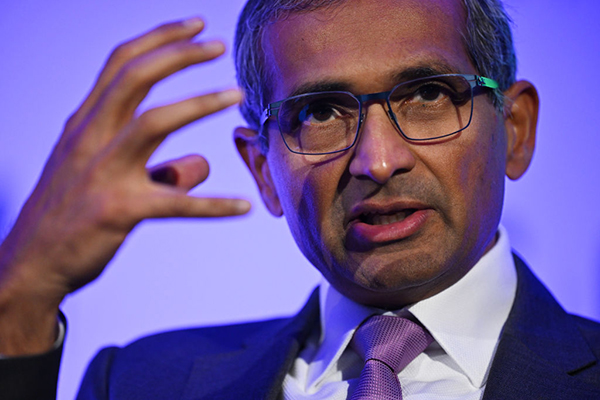
Deepak Nath, CEO of Smith+Nephew. Photo: Leon Neal/Getty Images.
Trading update for third-quarter to 30 September
- Adjusted revenue up 3.4% to $1.55 billion (£1.16 billion)
Guidance:
- Now expects full-year 2026 adjusted revenue growth of around 3%, down from 4%
- Now expects growth in full-year trading profit of around 4%, down from 8%
Chief executive Deepak Nath said:
“We remain focused on improving performance, enhancing operational efficiency and allocating capital to the highest-value opportunities across our business, in line with the RISE strategy, while continuing to consider all opportunities that could accelerate value creation in the best interests of shareholders.”
- Our Services: SIPP Account | Stocks & Shares ISA | See all Investment Accounts
ii round-up:
Medical device maker Smith & Nephew (LSE:SN.) has reduced annual sales hopes again, and this time also lowered profit guidance given weaker-than-expected demand in the US for knee and hip replacements.
Third-quarter sales to late September rose 3.4% from a year ago to $1.55 billion (£1.16 billion), matching analyst forecasts. Weak current fourth-quarter demand now sees management’s annual sales growth estimate reduced to 3% from 4%, with profit growth hopes cut to 4% from 8%.
Shares in the FTSE 100 company fell 2% in early UK trading having come into this latest news down around a tenth so far in 2026. Fellow orthopaedics maker Zimmer Biomet Holdings Inc (NYSE:ZBH) is up by a similar amount during that time. The FTSE 100 has gained around 7% year-to-date.
Smith & Nephew operates across the three divisions of Orthopaedics, Sports Medicine and ENT (Ear, Nose and Throat), providing products to repair or remove soft tissue, as well as advanced wound care.
Management confirmed it had approached Johnson & Johnson (NYSE:JNJ) about merging with the US healthcare giant's orthopaedics business, but talks came to nothing. As such, a full range of strategic options is now being considered.
At the end of 2025, the Watford headquartered company adjusted its performance improvement plan, with targets under the RISE strategy including increased product innovation, growing market share and improving efficiency.
A 2% beat in quarterly sales at Sports Medicine and ENT offset a 3% shortfall in Wound Care revenues. Orthopaedics sales matched analyst hopes, with other reconstruction demand offsetting soft knee and hip replacement sales.
Full-year results are scheduled for 1 March.
ii view:
Begun in 1856, Smith & Nephew today operates in more than 100 countries. Orthopaedics generated most sales in 2025 at 40%. That was followed by Sports Medicine & ENT at 31% and Advanced Wound Management the balance of 29%. Geographically, the US accounted for most sales last year at 54%, with other Developed markets 30% and Emerging Markets 16%.
For investors, tough market conditions and slower innovation in knee and hip replacements looks to leave annual Orthopaedics sales and profits below City hopes. Cuts to guidance now leaves management’s medium-term goal of 6-7% compound annual growth in profits to 2028 looking ambitious. US trade tariffs have previously impacted, with global tensions ongoing, while currency moves can affect the business.
- US midterm elections: one of best historical buy signals for equities
- Wild’s Winter Portfolios 2026: winning stocks revealed
- ii view: AstraZeneca bullish on potential blockbuster assets
More favourably, options for the Orthopaedics business remain under management consideration. A performance improvement plan remains ongoing. Bolt-on acquisitions have previously bolstered growth. Diversity in both products and geographical regions exists, while the payment of a dividend since 1937 now leaves the shares on a dividend yield of around 2.7%.
For now, a downgrading of sales and profit forecasts generates more caution, although potential M&A and exposure to generally defensive healthcare demand will likely keep long-term investors interested.
Positives:
- Product and geographical diversification
- Exposure to favourable demographics
Negatives:
- Subject to US trade tariffs
- Competition not standing still
The average rating of stock market analysts:
Hold
These articles are provided for information purposes only. Occasionally, an opinion about whether to buy or sell a specific investment may be provided by third parties. The content is not intended to be a personal recommendation to buy or sell any financial instrument or product, or to adopt any investment strategy as it is not provided based on an assessment of your investing knowledge and experience, your financial situation or your investment objectives. The value of your investments, and the income derived from them, may go down as well as up. You may not get back all the money that you invest. The investments referred to in this article may not be suitable for all investors, and if in doubt, an investor should seek advice from a qualified investment adviser.
Full performance can be found on the company or index summary page on the interactive investor website. Simply click on the company's or index name highlighted in the article.