Tesco target upgraded
5th April 2016 14:21
by Lee Wild from interactive investor
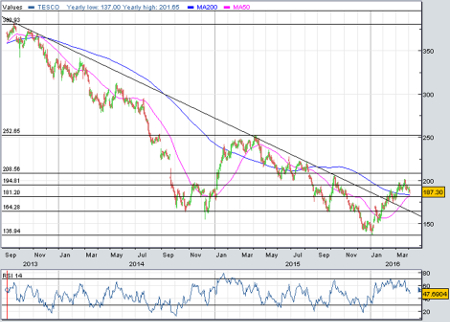
Only three months ago looked dead and buried. A price war triggered by German discount retailers and internal incompetence under old management made sure of that. But with Dave Lewis at the helm for over 18 months and a better-than-expected Christmas behind it, investors have piled back in. In fact, the share price has risen so fast one analyst has been forced to rethink targets just a week before the supermarket's full-year results.
Tesco shares, currently up 25% this year, were up as much as 35% in 2016, briefly topping 200p last month for the first time since mid-October. By comparison, the index is down 3% this year.
Since last month's 201p high, however, Tesco's share price has fallen by 7% versus a modest 1.6% decline for the wider market. There are a number of unresolved headwinds facing Lewis and his team, and there is some scepticism among investors about the likelihood of further gains, certainly near-term.
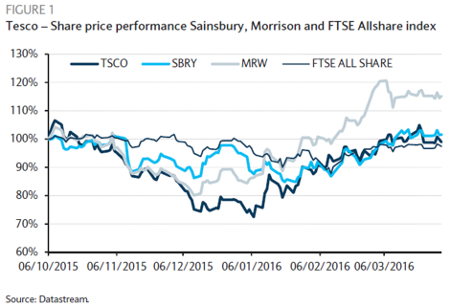
"It is hardly surprising," says the European food retail team at Barclays, however: "The stock's strong first-quarter performance only really cancels out a weak fourth-quarter - since its first-half results, the share has only fractionally outperformed the FTSE All Share index (and has lagged and )."
The shares are only back where they were on the eve of Tesco's interim results last October, "so we hesitate to agree that the stock has really outperformed to any great extent," says analyst James Anstead.
"Whereas our January upgrade was primarily based on valuation, since then Tesco has demonstrated much clearer top line momentum than for many years. Moreover, the weakness of sterling brings a clear translation benefit - and potentially an inflation benefit - and Casino's Thai disposal had positive valuation implications."
Few surprises in store
There should not be too many surprises when results for the 52 weeks ended 27 February are published on 13 April. January's update means we're only missing data from the last seven weeks of the period. Helpfully, Barclays has extrapolated the market share data from Kantar Worldpanel and come up with fresh estimates.
Look for UK like-for-like sale growth of 0.8% for the fourth quarter and a 1.3% increase for the group. Total sales, excluding the Korean business sold to private equity-led consortium last year, are seen down 3% over the 12 months to £55.1 billion.
Tesco said a year ago that operating profit should come close to the 2014/15 figure, adjusted for Korea, at £940 million. Anything over that would be reinvested back in to the business, so Barclays goes for £921 million, or margin on 1.7%, giving adjusted earnings per share (EPS) of 5p, down from 8p last time.
But what about 2016/17?
"We would certainly be wary of expecting a very specific comment in terms of the company's own profit expectations for 2016/17, since the turnaround is still in its early stages and there are many unknowns (ASDA's intentions, the EU referendum and its impact on FX and consumption)," says Anstead.
"Having said this, a detailed consensus does exist - compiled by VUMA on behalf of Tesco - so even if Tesco makes no specific comment then we think that could be taken as a broad endorsement of consensus."
Current consensus for the current financial year is for adjusted operating profit of £1.25 billion on static sales of £43.8 billion. UK like-for-like sales are tipped to drop by 0.2% over the year, slightly worse than Barclays, which thinks they'll be flat over the 12 months.
"Overall, we expect the market to have a greater degree of confidence on Tesco's FY 2016/17 profit at the end of 13 April than it does today, but we do not necessarily expect it to be an absolute level of confidence and we do not expect Tesco to push expectations higher."
Still, Anstead feels there is upside on the renewed trading momentum and believes that the market tends to worry less about high earnings multiples - Tesco trades on 24 times EPS estimates for 2016/17 - in the early stages of turnaround situations. He repeats his 'overweight' rating and increases his price target from 190p to 215p.
This article is for information and discussion purposes only and does not form a recommendation to invest or otherwise. The value of an investment may fall. The investments referred to in this article may not be suitable for all investors, and if in doubt, an investor should seek advice from a qualified investment adviser.