ii view: WH Smith predicts profit no worse than forecast
Selling its UK high street business last year before suffering an overstated profit position. We assess prospects for this struggling retailer.
16th September 2026 15:33
by Keith Bowman from interactive investor
Full-year trading update to 31 August
- Revenue up 5%
- Expects headline pre-tax profit of £75 million
- Expects year-end net debt of £325 million
ii round-up:
Travel focused retailer WH Smith (LSE:SMWH) today flagged increased annual revenue but adjusted profit at the bottom end of management’s previous forecast.
Total group revenue up 5% year-over-year includes the opening of six new ‘one-stop-shops’ for its UK division. Central costs and interest charges have reduced, but increased promotional sales activity, reduced advertising and cost increases elsewhere mean management now predicts profit of £75 million – the bottom end of a previous £75-90 million estimate.
Shares in the FTSE 250 company fell marginally in UK trading having come into this latest news down by close to half so far in 2026. Fellow food-on-the-go retailer Greggs (LSE:GRG) is up by around 4% during that time. The FTSE 250 index is up 7% year-to-date.
- Our Services: SIPP Account | Stocks & Shares ISA | See all Investment Accounts
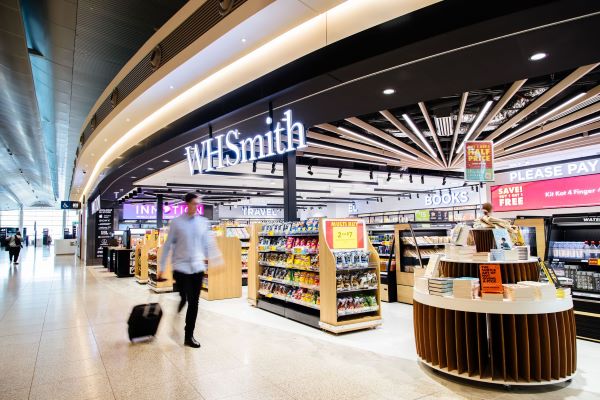
WH Smith’s previous sale of its UK high street business now leaves it focused on more than 1,000 travel location stores at airports, railway stations, motorway service stops, and hospitals, in both the UK and overseas.
UK final quarter growth of 7% is up from 5% the previous quarter, supported by growth across all category locations and assisted by refurbished stores for airports including Heathrow and East Midlands. The gains follow management’s drive to widen the customer offering and increase basket size in high footfall locations.
A 5% increase in fourth-quarter North America revenues compares with 9% growth in Q3, hindered by reduced airport passenger volumes and softer consumer demand.
Sales for its Rest of the World (ROW) division fell 4%, hit by store closures and an exit from Norway, with exits from Denmark, Sweden and the Netherlands all due in 2027.
A share fundraising of £103 million in June is expected to leave net debt as of late August at £325 million. That’s in-line with management’s two times leverage ratio.
Full-year results and a management update on key priorities for the year ahead are scheduled for 12 November.
ii view:
Started by Henry Walton Smith in 1792, the group today sells a variety of items including newspapers, books, stationery, food-on-the-go items and technology accessories. A constituent of the FTSE 250 index, other food-on-the-go rivals include Marks & Spencer Group (LSE:MKS) and McDonald's Corp (NYSE:MCD).
Airport related sales accounted for 73% of all revenues as of late February, with the balance split between rail, hospitals and service stations. Geographically, the UK accounted for 53% of sales, followed by North America at 27%, and ROW the balance of 20%.
For investors, store exits and restructuring charges are expected to see a charge of up to £150 million taken within the annual results. An expected full-year adjusted profit of £75 million is down from an earlier year forecast of up to £115 million. Elevated fuel prices now overshadow both air passenger demand as well as squeezing consumer spending more broadly, while interim results in April saw the dividend payment suspended to help repair the group’s finances.
- 10 hottest ISA shares, funds and trusts
- Insider: bargain hunters swoop on two struggling FTSE 250 stocks
- Another setback for AB Foods but Currys doing better
To the upside, a strategy to exit countries lacking sufficient scale and profitability as well as reviewing underperforming businesses such as that of tech products ‘InMotion’, is being pursued. Expected year-end net debt of £325 million is down from £496 million in late February. Diversity of product and geographical location exist, while an estimated price-to-net asset value of under three times is comfortably below the three-year average.
In all, expected long-term growth in global air passenger volumes offers hope, although the shares have performed terribly, so more cautious investors are likely to await evidence of a profit recovery before taking action.
Positives:
- Product and geographical diversity
- Exposure to expected growth in air travel
Negatives:
- Uncertain economic outlook
- Overseas ops bring currency volatility
The average rating of stock market analysts:
Strong hold
These articles are provided for information purposes only. Occasionally, an opinion about whether to buy or sell a specific investment may be provided by third parties. The content is not intended to be a personal recommendation to buy or sell any financial instrument or product, or to adopt any investment strategy as it is not provided based on an assessment of your investing knowledge and experience, your financial situation or your investment objectives. The value of your investments, and the income derived from them, may go down as well as up. You may not get back all the money that you invest. The investments referred to in this article may not be suitable for all investors, and if in doubt, an investor should seek advice from a qualified investment adviser.
Full performance can be found on the company or index summary page on the interactive investor website. Simply click on the company's or index name highlighted in the article.