Jet2 pays big price for flying record passengers
Half-year results broke records but pricing initiatives had implications for the bottom line. ii's head of markets runs through the numbers of Britain's third-largest airline.
18th November 2026 08:27
by Richard Hunter from interactive investor
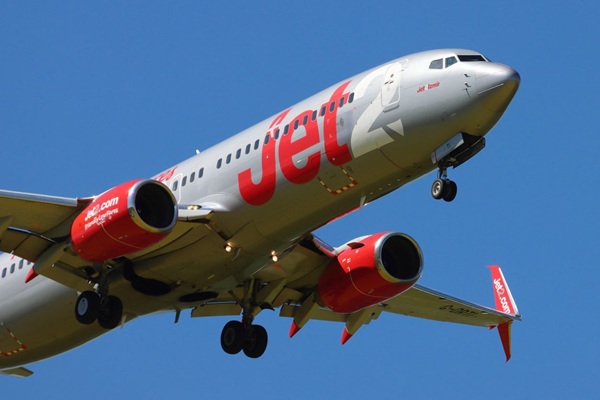
Jet2 Ordinary Shares (LSE:JET2) has leaned heavily on reducing pricing which has had the desired effect on increased passenger numbers, but has also sharply reduced profit for the period.
- Our Services: SIPP Account | Stocks & Shares ISA | See all Investment Accounts
The backdrop is well known, with the ongoing conflict in the Middle East combining with volatile jet fuel prices to muddy the outlook. For its part, Jet2 has significant protection for the remainder of the year from its foreign exchange and fuel hedging positions, but for the unhedged position the group has reduced its winter seat capacity by 240,000 seats.
The yield per passenger fell by 14% for flight-only customers during the six months ended 30 September, as the group needed to invest in lower pricing to attract new business in the height of the summer season. This seems to have had the desired effect, with flight-only customers rising by 20% to 5.7 million and with overall passengers increasing by 9% to a new record of 15.4 million.
- Stockwatch: this FTSE 250 share remains on my buy list
- 10 hottest ISA shares, funds and trusts: week ended 13 November 2026
As a result of the pricing initiatives, the load factor also increased by 1.5% to 89.7%, achieved despite the lack of visibility of bookings. However, this came at a cost. While revenues for the half rose by 5% to £5.63 billion (another record), operating profit fell by 18% to £588.3 million and pre-tax profit by 19% to £652.2 million.
Alongside planned and ongoing investment in the new slots at Gatwick, a multi-year technology partnership to harness AI in terms of personalised offers and price optimisation and the delivery of new aircraft, the strength of the balance sheet remains intact, if tested.
- Experts predict another great year for stock markets in 2027
- UK funds: stockpicking that stands out from the crowd
Another headwind comes in the form of a trend which has continued, namely that customers are driving a “fast-moving late booking” environment, which increases the airline’s difficulty in planning, let alone gauging costs which are partly fixed. In addition, losses are traditionally expected in the second half as the group prepares for next summer, driven by increased capacity and marketing spend, along with recruitment costs, are likely to be responsible for those headwinds.
The group is therefore declaring that to provide a full-year estimate when a proportion of winter customers are yet to book would be premature, and that it will have a much better handle on the situation at the time of its third-quarter update in February.
- eyeQ: this successful call triggers tactical trading signal
- Insider: a ‘very high conviction’ £1m director deal
Of course, the macro environment remains cloudy and the propensity of customers to book late will continue to provide challenges. More broadly, investing in airline shares generally has never been for the faint hearted. The ferocity of competition and economic pressure remain as potential challenges, as do some of the other issues which have historically blighted the sector, such as virus outbreaks, industrial action, volcanic dust clouds and higher fuel costs. The current macroeconomic and geopolitical concerns add to a potentially dangerous mix, underlying some of the potential hazards of investing in the airline sector.
However, and contrary to popular belief, Jet2 is no minnow. It is the third largest airline in the UK behind British Airways and easyJet, ahead of TUI and Virgin Atlantic. The company has now decided to underline its £2.7 billion market cap size by switching from AIM to the Main Market, which is likely to complete in December. While the date will narrowly miss the cut off for December inclusion, Jet2 should then ease into the FTSE250 at the following reshuffle in March.
- Pensions and inheritance tax: what new rules really mean for your estate
- Sign up to our free newsletter for investment ideas, latest news and award-winning analysis
Management sees this as a natural evolution to a full listing and underlines its confidence in prospects for the business, as does, for example, the £250 million share buyback programme which is ongoing. The shares have had a difficult run and are 22% below the June 2025 peak, after which a profit warning last September put the skids on the price. That fall has been softened by a 14% bounce in the price over the last year, in line with the gain of the wider FTSE250, some of which was a read across from the takeover bid for easyJet and the possibility of further M&A activity in the sector.
However, it remains to be seen whether Jet2 can break out of the current holding pattern, and the shares have met with a disappointed response in early trade. On the other hand, it is not unusual for investors to have something of a soft spot for the airline sector. Indeed, with its robust balance sheet and clear expansionary plans, the market consensus of Jet2 as a buy reflects some overriding optimism, although the share price reaction today may put some pressure on that view.
These articles are provided for information purposes only. Occasionally, an opinion about whether to buy or sell a specific investment may be provided by third parties. The content is not intended to be a personal recommendation to buy or sell any financial instrument or product, or to adopt any investment strategy as it is not provided based on an assessment of your investing knowledge and experience, your financial situation or your investment objectives. The value of your investments, and the income derived from them, may go down as well as up. You may not get back all the money that you invest. The investments referred to in this article may not be suitable for all investors, and if in doubt, an investor should seek advice from a qualified investment adviser.
Full performance can be found on the company or index summary page on the interactive investor website. Simply click on the company's or index name highlighted in the article.