Will Burnham hike CGT to fund personal allowance rise?
A radical policy suggestion would see most workers and retirees gain but inflict further pain on investors who’ve endured several negative reforms to wealth taxes in recent years.
22nd September 2026 13:54
by Craig Rickman from interactive investor
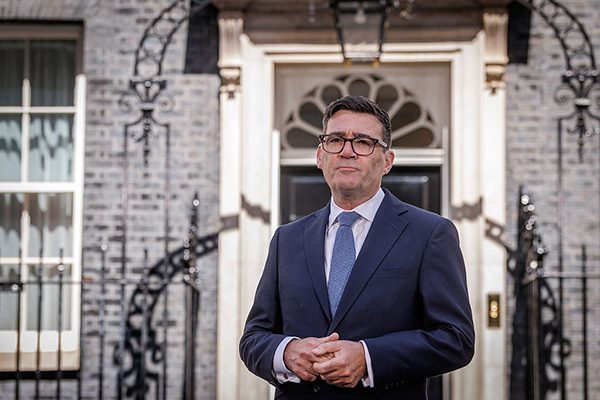
Prime Minister Andy Burnham has made no secret of his desire to raise the threshold that people start paying income tax. Before the Makerfield MP assumed the UK’s top political post, he commented that it’s the core policy change his constituents requested to protect their finances against the rising cost of living.
- Our Services: SIPP Account | Stocks & Shares ISA | See all Investment Accounts
The various income tax and national insurance (NI) thresholds have been frozen since 2021 and aren’t due to rise until 2031, dragging more people into the tax net and shunting others into higher thresholds as their incomes rise naturally over time.
A glaring stumbling block for Burnham, as he’s apparently found early in his premiership, is that fiscal prudency means aspiration and reality don’t always chime.
The prime minister and his chancellor, John Healey, have committed to the government’s iron-clad fiscal rules, and soaring borrowing costs due to events in the Middle East may have significantly eroded the headroom. Economists believe the £23 billion buffer from Spring has halved to around £12 billion, with talk ahead of the 2026 Budget centring on tax rises rather than giveaways.
But Labour donor, Dale Vince, believes he has a solution. And it’s a radical one.
The ‘green industrialist’ and founder of Ecotricity proposes that the £12,570 tax-free figure should be bumped up to £15,270, roughly the level it would’ve been in absence of the freeze. The tax break could be funded by the Bank of England ending interest payments to banks on their reserves and, in part, by significant hikes to capital gains tax (CGT).
According to The Telegraph, the government is weighing up the idea for this year’s Autumn Budget. Increasing the personal allowance by £3,000 could put an extra £600 a year in household pockets, and Burnham is committed to addressing household cost pressures – no small task with UK inflation accelerating in recent months.
The National Institute of Economic and Social Research’s (NIESR) modelling commissioned by Vince, reckons this could have positive effects on the UK economy, with energised consumer spending delivering a 1.2% boost to GDP growth in year one.
Winners of raising the personal allowance
Jacking up the tax-free personal allowance is often billed as a policy to support lower paid members of society. While this group indeed stand to benefit, millions of others receive a tax break too. In fact, anyone earning up to £125,140 – the point where the personal allowance is fully withdrawn - could potentially pay less tax under such a policy. That makes up almost 97% of taxpayers in the UK, according to gov.uk data.
- 5 smart steps to navigate pre-Budget uncertainty
- Wealth warning: when acting on rumours can cost you a fortune
Ending the deep freeze on this threshold may also solve the problem, for several years at least, of the full state pension breaching its limit and retirees paying tax on the excess.
The full state pension is currently £12,548 a year but is expected to jump £488 to £13,036 in April 2027 after three-month wage growth under the triple lock was confirmed at 3.9%. Although this figure is subject to revision, in the absence of policy intervention, from the new tax year retirees whose sole income is from the state pension will be landed with an HMRC bill.
Healey and Burnham have promised to honour Rachel Reeves’s pledge to address this looming issue, but so far have offered scant detail about how things will work. Increasing the personal allowance is the simplest fix, albeit the most expensive one.
Losers of hiking CGT
Vince has proposed equalising CGT rates with income tax gradually over a period of five years, a significant change that would see the top rate rise to 45% in England, Wales and Northern Ireland, and 48% in Scotland – higher than any other European country.
This would not be warmly received by investors, especially as the CGT regime has endured a relentless assault in recent years. The annual tax-free exemption has been hacked from £12,300 to £3,000, while the headline rates on sales of shares and other assets were increased from 10% to 20% at the basic rate, and from 18% to 24% at the higher rate, in 2024.
Among the casualties of further CGT increases are landlords, and investors with holdings outside of tax wrappers such as pensions and individual savings accounts (ISA). The number of people impact is dwarfed by those who’d benefit from a higher personal allowance, but that won’t make such a policy palatable.
CGT receipts surged by a staggering 89% during the 2024-25 tax year, according to latest figures from HMRC, hitting a record £24.2 billion, while the number of people paying the tax increased by 45% to 584,000.
We can attribute a sizeable chunk of this stark increase to investors selling assets ahead of the Autumn Budget 2024, in fear CGT rates would rise, with rumours running wild that the system could be brought in line with income tax. As noted above, the government ultimately opted for a tamer increase.
- What you need to know about ISAs and how they’ll soon change
- Record CGT receipts: what you need to know ahead of the Budget
One possible reason for the less aggressive hike is that jacking up taxes, notably CGT, offers no guarantee of increased receipts. That’s because pushing rates beyond a level deemed acceptable to stomach a tax bill, something referred to as the Laffer Curve, can spark a shift in behaviour, with investors holding onto assets instead of realising gains in the hope that rates will revert in the future. There’s also no CGT to pay on death, offering a further incentive to only realise a taxable profit if required.
Paul Johnson - provost of The Queen's College, Oxford and former director at the Institute for Fiscal Studies (IFS) - was less than convinced by the numbers, describing them on social media site X as “nonsensical.”
He added that HMRC estimates a 10-percentage point increase in CGT would trigger a £3.5 billion fall in revenue. “[The] exact magnitude can be disputed, but it sure as heck wouldn’t raise close to £14 billion,” he argued.
Considerations for increasing the personal allowance
Raising the personal allowance might sound straightforward, but there are related parts that Healey and Burnham would be wise not to overlook.
The first relates to national insurance (NI). Employees and self-employed workers pay no NI on the first £12,570 of earnings, with rates of 8% and 6%, respectively, on anything between that figure and below £50,270.
The government would ultimately need to decide whether any increase to the tax-free threshold applies to NI, too - something that would of course make any hike far more expensive for the Treasury but more generous for workers.
Vince’s and NIESR’s recommendations calculate a £600 tax saving (20%) based on a £3,000 personal allowance hike, so we can infer hiking the NI threshold was excluded.
We should note that NI and income tax thresholds don’t have to be aligned. In the 2021/22 tax year, NI kicked in once earnings exceeded £9,568, whereas the personal allowance was £12,570 - so the point at which workers start paying NI could stay put even if the personal income tax allowance rises. It would, however, mean returning to a framework with less consistency and simplicity.
A further complication relates to the gradual withdrawal of the personal allowance once earnings exceed £100,000. The £125,140 income point where the £12,570 tax-free is fully lost dovetails with the additional rate threshold. The overlap caused by hiking the personal allowance but failing to lift the 45% band could see effective tax rates of either 67.5% or 69.5% (depending on whether the individual pays 2% NI) on a portion of income, creating more mess and punishing tax rates in a pocket of the tax system that’s long been crying out for reform.
What are the odds?
Hikes to CGT are one of the few prevalent tax-hike rumours ahead of 2026’s set-piece fiscal event. That said, similar reports have emerged before every budget from the past few years, and bringing parity with the income tax framework is of course yet to come to pass.
- The pension trick saving parents thousands in tax and free childcare
- Seven tips to boost your pension and cut your tax bill
With the potential tax take of sterner CGT rates tricky to forecast, it’s hard to see how the Treasury could confidently calculate such a drastic reform – even if phased in over time - would help offset a significant increase to the personal allowance.
In addition, equalising CGT rates with income tax would surely need to be supported with some kind of indexation or taper relief, like the system that existed before the regime was overhauled in 2008.
This policy rewarded investors for holding assets for longer periods, something that leans into the retail investing culture the government is trying to foster. In absence of a taper or equivalent incentive, investors could be clobbered with CGT by merely increasing their wealth in-line with inflation.
If the government does decide to uptick the personal allowance ahead of the 2031 schedule, presumably the increase will be smaller than £3,000, especially with discipline needed to satisfy its self-imposed fiscal rules and the limited options to offset giveaways given the pledge not to raise the headline rates of income tax, employee NI and VAT.
These articles are provided for information purposes only. Occasionally, an opinion about whether to buy or sell a specific investment may be provided by third parties. The content is not intended to be a personal recommendation to buy or sell any financial instrument or product, or to adopt any investment strategy as it is not provided based on an assessment of your investing knowledge and experience, your financial situation or your investment objectives. The value of your investments, and the income derived from them, may go down as well as up. You may not get back all the money that you invest. The investments referred to in this article may not be suitable for all investors, and if in doubt, an investor should seek advice from a qualified investment adviser.
Full performance can be found on the company or index summary page on the interactive investor website. Simply click on the company's or index name highlighted in the article.