Beyond SpaceX: trusts and the hunt for tomorrow’s IPOs
SpaceX was the IPO that made everything else look small, but it shouldn’t eclipse other stories worth following, argues a Kepler analyst who considers investment trusts looking for tomorrow’s winners before the rest of the market finds them.
11th September 2026 14:03
This content is provided by Kepler Trust Intelligence, an investment trust focused website for private and professional investors. Kepler Trust Intelligence is a third-party supplier and not part of interactive investor. It is provided for information only and does not constitute a personal recommendation.
Material produced by Kepler Trust Intelligence should be considered a marketing communication, and is not independent research.
Phileas Fogg bet he could circle the world in 80 days. The 2026 IPO market has embarked on a journey of its own, with a succession of unexpected names, unlikely winners and, ultimately, a record-breaking blockbuster.
Across the first half of the year, activity picked up across the major markets: Europe began to stir, Asia continued to produce new listings and New York eventually supplied the year’s headline act. Worldwide, 509 companies raised $193.6 billion (£143 billion) through IPOs in the first half alone, with proceeds up 210% on the same period last year.
Within Europe, a standout name was CSG NV (EURONEXT:CSG), a Czech defence and industrial group that, before Elon Musk entered the stage, had raised more through its IPO than any other company in the world. It was also the largest defence IPO ever recorded, raising €3.8 billion (£3.3 billion) at a €25 billion valuation, a remarkable milestone for a company that barely registered outside its home market.
Additionally, another European giant Bending Spoons SpA (NASDAQ:BSP) brought its collection of consumer technology businesses to Nasdaq and further east, Zhejiang Zhenshi New Materials rode the renewables theme, with the fibre fabrics maker’s Shanghai listing raising 2.9 billion yuan (£319 million) and its shares surging 122% on debut.
Not every name worth watching has listed yet, though: some very interesting companies remain firmly private while showing real interest in coming to market, from financials like Revolut, although it has signalled that a stock market debut remains several years away, to AI players like Anthropic, the mastermind behind the LLM Claude, which has taken concrete steps towards an IPO and is widely seen as a potential listing candidate before the end of the year.
However, in June 2026 came the deal that made everything else look small. Space Exploration Technologies Corp Class A (NASDAQ:SPCX) raised approximately $86 billion in its IPO at a valuation of around $1.77 trillion, making it the largest listing in history. It was the sort of transaction capable of distorting the statistics around it, but also a remarkable demonstration of how much value can now be created before a company ever reaches the public markets.
Look across this year’s biggest listings, though, and a pattern emerges: most are trading below or barely above their offer price only months on. The real money, in almost every case, was made before that first day of trading, not after it. That’s the case for taking private markets seriously in the first place, money that can get into a business years before it ever files for a listing, and stay there for as long as the opportunity justifies, has a genuine structural advantage ordinary public-market investing simply doesn’t offer. The IPO, when it eventually comes, is often just the moment the rest of the market catches up to a price that patient capital locked in years earlier.
So, what we are trying to, perhaps not very subtly, state is that the story does not end with SpaceX. Some companies have already made the leap into public markets and are worth a look; others are preparing to follow; and some other interesting businesses remain firmly private. The journey from private company to public company is becoming longer, but potentially more valuable and considerably less predictable, and for investors, there is plenty to discover along the way and very different ways to access them.
The SpaceX effect
For Scottish Mortgage Ord (LSE:SMT), SpaceX’s IPO was a spectacular milestone in a journey that had started almost eight years earlier. Baillie Gifford first backed the rocket company for SMT in 2018, valuing SpaceX at around $31 billion, when Starlink was still in its infancy and Starship a long way from commercial reality. The attraction was not what SpaceX was at the time, but what it might become.
SMT’s managers saw a company capable of reshaping the economics of space: reusable rockets making launches cheaper and more frequent; Starlink turning that capability into a global communications network; and Starship taking the whole operation to another scale again. The investment required patience and plenty of tolerance for uncertainty, but the eventual numbers are extraordinary. SMT’s initial £151.1 million investment had grown to around £3.78 billion by the time SpaceX listed, roughly 25 times the original capital.
RIT Capital Partners Ord (LSE:RCP) got there too. Chief executive Maggie Fanari had spent years building a direct relationship with SpaceX, so that when an opportunity to invest arose, the team was already positioned to act on it rather than starting from scratch. That patience paid off: RCP built access years before this year’s IPO, at around $40 a share, and one of its private funds went further still, taking a position at just $4. RCP is still sitting on a gain of more than three times its cost, even after the stock’s sharp pullback since listing.
SpaceX priced its shares at $135 and began trading on Nasdaq on 12 June 2026, raising approximately $86 billion at a valuation of around $1.77 trillion, comfortably the largest IPO in history. The first few days were everything the hype suggested. Shares surged past $225 as investors scrambled for exposure to a company that had spent years frustrating public-market investors by staying private, before falling by more than half from their peak within weeks; they now trade at $143, only a small premium to the offer price. Second-quarter revenue of $7.8 billion, up 92% year on year, hints at why the market has grown more cautious even as the business keeps investing hard. SMT held SpaceX through plenty of volatility and uncertainty before the market ever got the chance to price it. AI looks like it’s here to stay, and space looks set to be one of the defining growth industries of the next decade; SpaceX will likely keep dominating headlines for a while yet, but it is one company, and we think the opportunities extend far beyond it.
Beyond the rocket ship
SpaceX may have dominated the US listings market, but it’s far from the only story worth following. The table below ranks this year’s 10 largest US listings by deal size, and SpaceX’s neighbours on that list are a useful reality check on their own.
TOP 10 US IPOS
| Company | IPO date | IPO price ($) | Return from IPO | Deal size ($) | Market cap ($) |
| Space Exploration Technologies Corp Class A (NASDAQ:SPCX) | 12/06/26 | 135 | 4.20% | 75.00bn | 1.91trn |
| SK hynix Inc ADR (NASDAQ:SKHY) | 10/07/26 | 149 | 10.70% | 28.13bn | 856.53bn |
| Cerebras Systems Inc Class A (NASDAQ:CBRS) | 14/05/26 | 185 | -0.30% | 5.55bn | 43.84bn |
| Innio NV (NASDAQ:INIO) | 04/06/26 | 27 | -25.70% | 2.43bn | 15.05bn |
| Madison Air Solutions Corp Class A (NYSE:MAIR) | 16/04/26 | 27 | -4.90% | 2.23bn | 12.88bn |
| Fervo Energy Co Class A (NASDAQ:FRVO) | 13/05/26 | 27 | -33.40% | 1.89bn | 5.30bn |
| Blackstone Digital Infrastructure | 14/05/26 | 20 | 1.20% | 1.75bn | 2.04bn |
| Bending Spoons SpA (NASDAQ:BSP) | 01/07/26 | 29 | 40.90% | 1.68bn | 24.56bn |
| Quantinuum Inc Class A (NASDAQ:QNT) | 04/06/26 | 60 | -20.00% | 1.68bn | 12.64bn |
| Pershing Square Inc (NYSE:PS) | 29/04/26 | 50 | -27.00% | 1.66bn | 14.60bn |
Source: Stock Analysis (SEC filings), as of 01/09/2026. Past performance is not a reliable indicator of future results
SK hynix Inc ADR (NASDAQ:SKHY)’s presence on this list is really an accessibility story rather than a fresh listing: the South Korean memory giant has traded in Seoul since 1996, and its Nasdaq ADR debut was designed to close what analysts call the “Korea discount”, years of trading cheaper than US rival Micron Technology Inc (NASDAQ:MU) simply because international investors couldn’t easily buy Korean shares.
Elsewhere on the list, Cerebras Systems Inc Class A (NASDAQ:CBRS), an AI chipmaker whose Wafer-Scale Engine claims 58 times the capacity of NVIDIA Corp (NASDAQ:NVDA)’s leading chip, comes backed by a 750-megawatt compute deal with OpenAI, and BlackRock American Income Trust Ord (LSE:BRAI) already has a small amount of exposure. Fervo Energy Co Class A (NASDAQ:FRVO), a Bill Gates-backed geothermal developer, and Innio NV (NASDAQ:INIO), whose gas engines back up the same AI-driven power demand, the latter of which sits in BRAI’s portfolio at a similarly negligible weight. Bending Spoons is the standout, up sharply since its July listing, although it’s a European name at heart, more on that shortly.
That’s the public side of the story. Anthropic shows what’s still to come. SMT backed the business in August 2025 at a $183 billion valuation, with managers Tom Slater and Lawrence Burns arguing that Anthropic has become a leading choice among enterprise AI buyers, a growing number of whom now spend over $1 million annually on adoption. Its revenue has climbed from a $10 million annualised run rate in 2022 to $47 billion by May 2026, a trajectory RCP, another Anthropic backer, has called unprecedented, no software business in history has sustained 50%+ growth at this scale before. Anthropic has since filed confidentially for an IPO at a valuation approaching $1 trillion, in the same league as SpaceX.
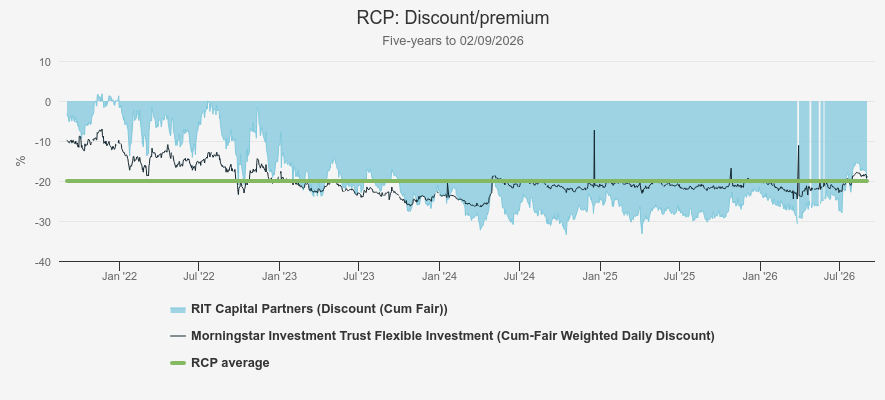
Moreover, we think RCP’s exposure runs deeper still, reaching further into the AI value chain through private funds, indirect stakes in Databricks, Scale, OpenAI and Stripe, spanning infrastructure, compute and the foundation models themselves. Databricks and OpenAI both look closest to a listing; Stripe has been the subject of speculation for years without committing to one. Accessed through RCP, which trades on a near 20% discount to NAV, that hard-to-access AI exposure sits alongside a genuinely diverse quoted portfolio and an uncorrelated strategies book designed to cushion the whole trust in periods of market stress.
RCP DISCOUNT
Source: Morningstar.
Europe rediscovers its nerve
If the US market has been about scale, we think Europe’s story this year has been about rediscovery, a reminder that the Continent’s businesses can still command real attention when they list, after a decade of watching its biggest names drift towards New York or simply stay private.
CSG is a great example. The leading defence group based in Prague raised €3.8 billion at a €25 billion valuation on Euronext Amsterdam, the largest defence IPO ever recorded, and did so before SpaceX had even confirmed a listing date. It barely registered outside its home market before floating, and yet for the first three months of 2026, it had raised more through its IPO than any other company on the planet, a sign of just how much appetite has built up for European defence and industrial names.
Technology has had its moment too, led by Bending Spoons, the Italian company that buys struggling but well-known apps, think Vimeo, Evernote and Meetup among them, and turns them profitable again. It floated on Nasdaq in July, but its headquartered in Europe, or Milan to be precise. One of its earliest backers is Baillie Gifford European Growth Ord (LSE:BGEU). The managers invested £4.4 million between August 2023 and February 2024, long before the turnaround story was obvious, a stake that had grown roughly 12 times over, to £53.2 million, by the time it listed this year.
Not every European name worth watching has listed yet. Revolut, the UK-founded digital bank, has secured its own banking licence, letting it capture the economics of a full bank rather than the thinner margins of a payments app, and now serves more than 70 million customers globally, with one in three new European bank accounts opened through the company. Molten Ventures Ord (LSE:GROW) has held it privately for years, and made partial realisations at 21x their initial investment, with Revolut now valued at around $75 billion.
Another example is ICEYE, a Finnish satellite manufacturer at the intersection of commercial space and European rearmament, which is now GROW’s largest holding, following a Series F round and contracts including one with the German armed forces, a valuation that alone would sit inside the FTSE 100. We think that’s one of the real attractions of GROW: a way to back companies still working at the leading edge before they become tomorrow’s giants.
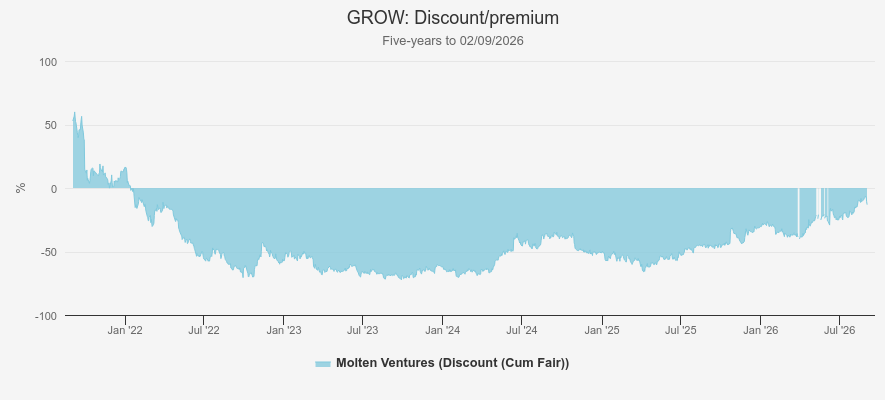
While the trust’s discount has narrowed sharply over the past year on the back of these developments, there could be a further wrinkle worth knowing: its current discount of near 13% is based on a NAV that hasn’t yet caught up with ICEYE’s latest write-up, meaning the real discount is wider still, and looks anomalously so given the strength already visible in its core positions.
GROW DISCOUNT
Source: Morningstar.
Hopping over to the UK, JPMorgan UK Small Cap Growth & Income (LSE:JUGI)makes the case for patience rather than pursuit. Rather than chasing fresh listings, the trust has stuck with two of its own post-IPO successes: Applied Nutrition (LSE:APN), which floated in 2024 and now sits among JUGI’s top 10 holdings, has delivered consistent earnings upgrades and recently struck a US agreement with Mondelez International Inc Class A (NASDAQ:MDLZ) that the managers expect to meaningfully support earnings over the medium term. The other is The Beauty Tech Group (LSE:TBTG), another 2024 listing, which has taken market share with new products such as LED face masks, repeatedly beating the conservative guidance it set at IPO.
Asia showcase
By sheer number of listings, no region has matched Asia this year, and Hong Kong has led the way, raising roughly HK$110 billion in the first quarter alone, a five-year high. Biotech has become a particular speciality: Hong Kong’s listed biotech index outperformed Nasdaq’s by roughly three to one in 2025, as Chinese healthcare companies increasingly choose the city over the US to sidestep tightening American scrutiny. Zhongji Innolight Co Ltd Ordinary Shares - Class H (SEHK:3308), whose optical components move data through AI systems for clients including Nvidia and Alphabet Inc Class A (NASDAQ:GOOGL), made that scale concrete in July, its HK$53.4 billion listing was Hong Kong’s largest in seven years, backed by sovereign cornerstone investors including Temasek and Abu Dhabi’s investment authority.
Baillie Gifford China Growth Trust Ord (LSE:BGCG) offers a useful way to think about what might follow, holding two of China’s biggest private companies, neither yet confirmed to list. ByteDance, TikTok’s parent, makes up around 10% of the portfolio; the completed separation of TikTok’s US operations into a US-based entity under non-Chinese control has removed a major source of regulatory uncertainty, and BGCG’s own reporting noted the company’s valuation was revised up roughly 30% on double-digit revenue and cash flow growth, and, in our view, may increase the chance of its listing. RedNote, a smaller 2% holding, sits at the intersection of social discovery and e-commerce, a model that’s proven lucrative for consumer platforms elsewhere in Asia.
India’s own path to market makes the case for patient capital especially well. Companies here can spend years, sometimes over a decade, clearing the regulatory and governance hurdles standing between a private business and a public listing: the National Stock Exchange’s own IPO took nearly 10 years to reach the market after a 2015 trading scandal, and is now expected to raise around Rs 30,000 crore, potentially entering the ranks of India’s 10 most valuable listed companies. Tax has proved just as significant a barrier, PhonePe reportedly paid close to $1 billion in capital gains tax simply to redomicile back to India before it could even begin the listing process.
Ashoka India Equity Investment Ord (LSE:AIE) is built for exactly this environment. Its board can allocate up to 15% of the portfolio to companies nearing a listing, understood explicitly as positions on their way to going public rather than permanent private holdings. OneSource Specialty Pharma shows what that patience can look like once it plays out: the pharmaceutical manufacturer listed in 2025 and is now AIE’s largest holding at 4.5% of the portfolio, and while it fell almost 20% to the end of January, it’s since rebounded strongly, up almost 40%. It’s a difficult part of the market to navigate from afar, one where regulatory clean-up and governance scrutiny can delay a listing for years, but AIE’s large, India-based research team gives it the access needed to work through it, the kind of expertise that can turn a genuinely hard market into a source of differentiated, idiosyncratic returns.
Final thoughts
SpaceX has made 2026 the year of the mega-IPO, but focusing too heavily on the rocket risks missing other opportunities. Some of the most interesting companies are not necessarily the ones ringing the opening bell today. Increasingly, they are the ones investors can identify years before they do, and the returns in this piece bear that out.
SMT’s experience with SpaceX is the clearest example: by the time public investors could buy the shares, its managers had already spent almost eight years backing the business, turning £151.1 million of initial capital into around £3.78 billion, a gain of roughly 25 times. RCP built its own access early too and it remains sitting on a gain of more than three times its cost even after the stock’s pullback since listing.
The pattern repeats well beyond space and AI, too: BGEU’s early stake in Bending Spoons, a consumer technology business, had grown roughly 12 times over by the time it listed, whilst GROW’s holding in Revolut, a fintech still private, has already appreciated some 21 times its original cost.
Defence, energy, financials, healthcare and industrials are all producing companies capable of attracting substantial capital of their own, while Europe, Asia and emerging markets are providing increasingly important routes to market, all of which feature in the pages above.
For investors, the opportunity may therefore be less about finding the next SpaceX and more about having the patience, access and flexibility to find tomorrow’s winners before the rest of the market does.
Kepler Partners is a third-party supplier and not part of interactive investor. Neither Kepler Partners or interactive investor will be responsible for any losses that may be incurred as a result of a trading idea.
These articles are provided for information purposes only. Occasionally, an opinion about whether to buy or sell a specific investment may be provided by third parties. The content is not intended to be a personal recommendation to buy or sell any financial instrument or product, or to adopt any investment strategy as it is not provided based on an assessment of your investing knowledge and experience, your financial situation or your investment objectives. The value of your investments, and the income derived from them, may go down as well as up. You may not get back all the money that you invest. The investments referred to in this article may not be suitable for all investors, and if in doubt, an investor should seek advice from a qualified investment adviser.
Full performance can be found on the company or index summary page on the interactive investor website. Simply click on the company's or index name highlighted in the article.
Important Information
Kepler Partners is not authorised to make recommendations to Retail Clients. This report is based on factual information only, and is solely for information purposes only and any views contained in it must not be construed as investment or tax advice or a recommendation to buy, sell or take any action in relation to any investment.
This report has been issued by Kepler Partners LLP solely for information purposes only and the views contained in it must not be construed as investment or tax advice or a recommendation to buy, sell or take any action in relation to any investment. If you are unclear about any of the information on this website or its suitability for you, please contact your financial or tax adviser, or an independent financial or tax adviser before making any investment or financial decisions.
The information provided on this website is not intended for distribution to, or use by, any person or entity in any jurisdiction or country where such distribution or use would be contrary to law or regulation or which would subject Kepler Partners LLP to any registration requirement within such jurisdiction or country. Persons who access this information are required to inform themselves and to comply with any such restrictions. In particular, this website is exclusively for non-US Persons. The information in this website is not for distribution to and does not constitute an offer to sell or the solicitation of any offer to buy any securities in the United States of America to or for the benefit of US Persons.
This is a marketing document, should be considered non-independent research and is subject to the rules in COBS 12.3 relating to such research. It has not been prepared in accordance with legal requirements designed to promote the independence of investment research.
No representation or warranty, express or implied, is given by any person as to the accuracy or completeness of the information and no responsibility or liability is accepted for the accuracy or sufficiency of any of the information, for any errors, omissions or misstatements, negligent or otherwise. Any views and opinions, whilst given in good faith, are subject to change without notice.
This is not an official confirmation of terms and is not to be taken as advice to take any action in relation to any investment mentioned herein. Any prices or quotations contained herein are indicative only.
Kepler Partners LLP (including its partners, employees and representatives) or a connected person may have positions in or options on the securities detailed in this report, and may buy, sell or offer to purchase or sell such securities from time to time, but will at all times be subject to restrictions imposed by the firm's internal rules. A copy of the firm's conflict of interest policy is available on request.
Past performance is not necessarily a guide to the future. The value of investments can fall as well as rise and you may get back less than you invested when you decide to sell your investments. It is strongly recommended that Independent financial advice should be taken before entering into any financial transaction.
PLEASE SEE ALSO OUR TERMS AND CONDITIONS
Kepler Partners LLP is a limited liability partnership registered in England and Wales at 9/10 Savile Row, London W1S 3PF with registered number OC334771.
Kepler Partners LLP is authorised and regulated by the Financial Conduct Authority.