ii view: soaring chip prices put Apple profits under pressure
Under a new chief executive and recently launching its first foldable phone. Analyst Keith Bowman assesses prospects.
3rd November 2026 11:45
by Keith Bowman from interactive investor
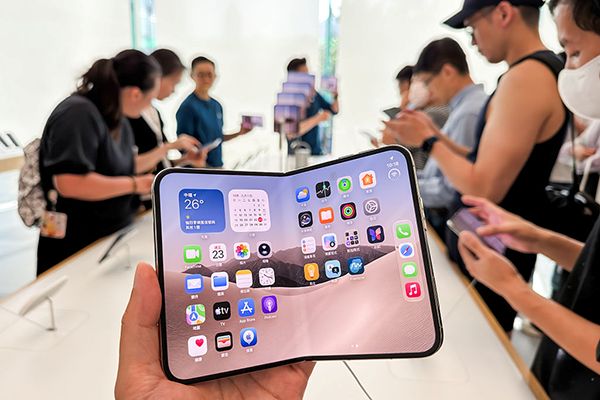
A person holds an iPhone Duo at an Apple store in Hong Kong. Apple’s first foldable smartphone went on sale on 23 October. Photo: Cheng Xin/Getty Images.
Fourth-quarter results to 26 September
- Revenue up 12% to $114.5 billion (£85.9 billion)
- Adjusted earnings up 14% to $2.10 per share
- Dividend of $0.27 per share, unchanged from Q3
New chief executive John Ternus said:
“Apple is proud to report a September quarter revenue record of $114.5 billion, up 12% from a year ago, with iPhone reaching a September quarter record and Services reaching an all-time high, capping off our best fiscal year ever.”
- Invest with ii: Buy US Stocks from UK | Most-traded US Stocks | Cashback Offers
ii round-up:
Apple Inc (NASDAQ:AAPL) detailed sales and profit that beat Wall Street forecasts, although the iPhone maker predicted a profit margin below analyst expectations because of higher memory chip and AI costs.
Fourth-quarter sales up 12% from a year ago to $114.5 billion (£85.9 billion) were behind a 14% gain in adjusted earnings to $2.10 per share. Analysts had forecast $113.4 billion and $1.99 per share respectively. A gross profit margin of 45-46% for the current first quarter is below Wall Street hopes of 46.1%.
Shares in the Dow Jones and Nasdaq tech titan fell 3% in post results US trading having come into these latest numbers up by a quarter so far in 2026. The Dow Jones and Nasdaq indexes are each up by almost a tenth during that time. Alphabet Inc Class A (NASDAQ:GOOGL), maker of rival smartphone software system Android, is down by a tenth year-to-date.
- 10 of the biggest IPOs on Wall Street in 2026
- Polar Capital Technology: the AI stocks I’m excited about in cognitive era
Former head of hardware engineering, John Ternus, now heads Apple. The group’s product line up now includes its first foldable ‘Duo’ phone as well as its most powerful ‘18 Pro’ and ‘18 Pro Max’ computer chip.
Fourth-quarter iPhone sales rose 17% from a year ago to $57.6 billion, giving annual 2026 sales of $254.1 billion, up from $209.6 billion a year ago.
Sales of services including Apple Music rose 10% year-over-year to $31.6 billion, an all-time high, with annual sales of $123.3 billion up from $109.2 billion in 2025.
iPad, as well as Wearable, Home and Accessories sales, each fell year-over-year to $6.2 billion and $8.3 billion respectively. Wall Street had forecast outcomes of $6.7 billion and $9 billion respectively. Apple has only recently launched a new range of home device products.
Geographically, fourth-quarter sales rose across all regions apart from Japan, where they fell marginally to $6.5 billion (Q4 2025: $6.6 billion). A quarterly dividend of $0.27 per share is unchanged from the prior quarter.
Broker Morgan Stanley reiterated its ‘overweight’ stance on Apple shares post the results, although lowered its price target marginally to $350 from $355.
ii view:
Started in 1976, rivals for its products and services include Samsung for phones, Meta Platforms Inc Class A (NASDAQ:META) for 3D headwear, Amazon.com Inc (NASDAQ:AMZN) for its home Alexa speakers, as well as TV and music streamers Netflix Inc (NASDAQ:NFLX), The Walt Disney Co (NYSE:DIS) and Spotify Technology SA (NYSE:SPOT). Geographically, North America dominated over this latest financial year at 41% of sales. That was followed by Europe at 27%, Greater China 18%, Asia Pacific 8% and Japan 6%.
For investors, soaring demand for computer chips to service AI requirements now raises concerns about sky-high chip prices and Apple's costs going forward. Elevated energy prices continue to pressure consumer spending as well as heightening production costs for manufacturers generally. A forecast price/earnings (PE) ratio above the three- and 10-year averages may suggest the shares are not obviously cheap, while global trade tensions persist and including those between the USA and China.
On the upside, the tie-in of customers using its services on their Apple devices generates high customer loyalty. New CEO John Ternus brings a major focus to product innovation given his previous position as head of hardware engineering. Product and geographical diversity exist, including exposure to payment services, while the dividend, although not a core attraction, has been increased consecutively for more than a decade, with the shares on a modest dividend yield of around 0.3%.
On balance, and while risks remain, this maker of popular consumer devices continues to justify its place in many already diversified investor portfolios.
Positives:
- Diverse geographical markets
- Strong customer loyalty
Negatives:
- Dependency on iPhone sales
- Currency headwinds
The average rating of stock market analysts:
Buy
These articles are provided for information purposes only. Occasionally, an opinion about whether to buy or sell a specific investment may be provided by third parties. The content is not intended to be a personal recommendation to buy or sell any financial instrument or product, or to adopt any investment strategy as it is not provided based on an assessment of your investing knowledge and experience, your financial situation or your investment objectives. The value of your investments, and the income derived from them, may go down as well as up. You may not get back all the money that you invest. The investments referred to in this article may not be suitable for all investors, and if in doubt, an investor should seek advice from a qualified investment adviser.
Full performance can be found on the company or index summary page on the interactive investor website. Simply click on the company's or index name highlighted in the article.