FTSE 100 shares round-up: Glencore, Anglo American, Halma, Babcock
Despite another session of losses for the index, there are some big individual blue-chip winners. City writer Graeme Evans looks at the big risers and fallers.
19th November 2026 13:11
by Graeme Evans from interactive investor
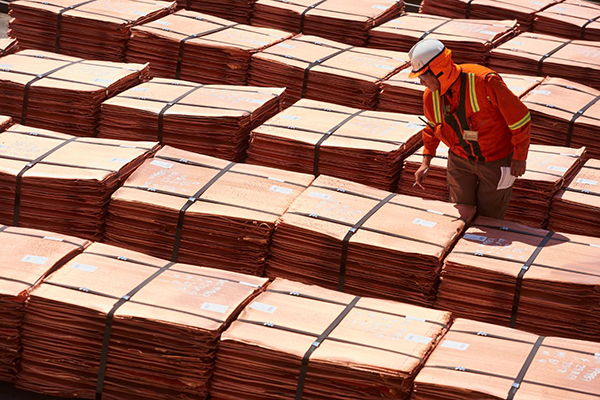
Lomas Bayas copper operation in northern Chile. Credit: Glencore.
Bargain hunters today focused on Glencore (LSE:GLEN), Anglo American (LSE:AAL) and the “undemanding” valuation of Halma (LSE:HLMA) but were unable to protect the FTSE 100 index from a fourth consecutive fall.
The benchmark’s modest reverse of 0.5% to a six-week low of 10,499 was driven by a weaker session by AstraZeneca (LSE:AZN), which accounts for 8% of the FTSE 100 by weight.
- Invest with ii: SIPP Account | Stocks & Shares ISA | See all Investment Accounts
British American Tobacco (LSE:BATS), Unilever (LSE:ULVR) and Compass Group (LSE:CPG) also fuelled the decline, as did the impact of ex-dividend day on Coca-Cola Europacific Partners (LSE:CCEP), Vodafone Group (LSE:VOD) and National Grid (LSE:NG.).
Offsetting some of the selling pressure, Rolls-Royce Holdings (LSE:RR.) rose by 26.6p to 1,356.8p and Barclays (LSE:BARC) topped the banking sector with an improvement of 4.7p to 415.8p.
There was also interest in the mining sector after yesterday’s copper price rout caused Glencore to slide 6%, Anglo American to lose 8% of its value and Chile’s Antofagasta (LSE:ANTO) to fall by 8%.
The unwind of the AI trade, dollar strength amid a repricing of US interest rate expectations, and the fallout from US midterm elections have acted as catalysts in the recent metals sell-off.
UBS noted copper, gold, aluminium and silver were down 8-15% over the last three weeks, with copper and aluminium recently breaking key technical levels to trigger further selling.
It said today that global macro events were largely responsible for the correction, rather than clear evidence of material demand weakness.
- What to do after copper mining stocks plunge
- Why buy-and-hold still wins when crash fears strike
- FTSE 100 shares round-up: big profits and hefty dividends
However, the bank added: “After breaking key support levels near-term price risks remain skewed to the downside, with US tariff risks/uncertainty limiting strategic buying on price weakness.”
New York-listed copper futures today steadied near $5.65 per pound, while the price of gold stood at $3,719 an ounce. It had been above $5,000 an ounce earlier this year.
The calmer session helped Glencore put back 8.5p at 469.9p, while Anglo American added 78p to 3,372p and Antofagasta rose 46p to 2,828p.
Glencore recently set out its ambition to double copper output to 1.6 million tonnes by 2035, while Anglo America is close to completing a copper-focused merger with Teck Resources.
The miners were joined on the risers board by quality compounder Halma, which rose 144p to 3,550p after the group of life-saving technology companies reported all-time highs for profit and revenue in the six months to 30 September.
The top line improved by 15.8% to £1.4 billion, fuelled by 30% organic growth in the photonics part of the Environmental & Analysis division.
This area has provided a tailwind to Halma’s performance in recent years and offers a profile that differs from that of the wider group in terms of pace, scale and longevity.
Having built its presence through the 2011 acquisition of Avo Photonics, Halma now generates 22% of its overall revenues through optical switches work with an unnamed hyperscaler in the data-centre space.
- Experts predict another great year for stock markets in 2027
- Government mulling worker pensions that mimic final salary
- The funds gaining an edge over the global stock market
Other products in the Halma portfolio include those to aid safety such as smoke alarms, devices to measure climate change and pollution, as well as medical instruments to test eyesight and hearing.
Today’s results leave Halma on track to deliver its 24th consecutive year of record adjusted profit, having grown the half-year figure by 21.1% to £327.7 million. Earnings per share rose by a fifth to 66.24p, while the dividend payable on 29 January is up 7% to 10.30p.
Halma also highlighted record levels of strategic investment, having completed eight acquisitions in the year to date at a cost of £571 million.
Chief executive Marc Ronchetti said: “Our longstanding aspiration is to double our earnings every five years, with organic growth and self-funded acquisitions contributing equally.
“With our organic engine already performing close to that aspiration, we challenged ourselves to accelerate M&A while maintaining our discipline and our returns. We started from a position of real strength, as a long-term acquirer with a track record built over decades.”
Morgan Stanley said today’s results showed strong growth momentum, with underlying margins ahead of expectations.
It increased its earnings per share estimate for 2026-27 by 1.6% but still cut its price target to 4,200p from 4,500p to reflect the recent derating of Halma’s peer group.
The shares trade on about 23 times forecast calendar year earnings, having fallen from the record price of 4,902p in early June. The bank added: “Halma remains a unique compounder, with valuation back to undemanding levels.”
- eyeQ: a bullish signal just before busiest week for flying
- Sign up to our free newsletter for investment ideas, latest news and award-winning analysis
- Stockwatch: this FTSE 250 share remains on my buy list
At the top of the FTSE 100, Babcock International Group (LSE:BAB) shares returned to form in the wake of strong half-year results.
Powered by its Nuclear and Aviation divisions, underlying operating profit beat City expectations with a rise of 13% to £227 million while free cash flow increased by 32% to £185.8 million. The interim dividend for payment on 15 January is up 12% to 2.8p a share.
The group’s operations range from through-life support of naval ships and submarines to complex engineering services in relation to nuclear decommissioning programmes. It also provides pilot training and airbase management.
New chief executive Harry Holt today highlighted continued momentum across the group, with around 90% of expected 2027 revenue under contract on 1 October.
He added.: “Alongside the UK and international growth of our core business, we are actively leveraging our capabilities to capture opportunities in two additional growth vectors: the hybrid nature of warfare and strengthening national strategic resilience.
“We are well positioned to deliver on our medium-term targets and the next phase of growth, with a clear strategy and significant opportunities ahead for long-term shareholder value creation.”
The shares were among last year’s best performers in the FTSE 100 index, only to fall 18% over the course of this year. They rallied 66p to 1,041p in today’s session, which compares with Peel Hunt’s 1,409p price target.
The broker said: “The strong first-half delivery reinforces our confidence in Babcock’s earnings trajectory.
“We see scope for sustained mid-teens EPS growth over the medium term, supported by structurally growing defence and nuclear markets, margin progression and balance sheet optionality.”
These articles are provided for information purposes only. Occasionally, an opinion about whether to buy or sell a specific investment may be provided by third parties. The content is not intended to be a personal recommendation to buy or sell any financial instrument or product, or to adopt any investment strategy as it is not provided based on an assessment of your investing knowledge and experience, your financial situation or your investment objectives. The value of your investments, and the income derived from them, may go down as well as up. You may not get back all the money that you invest. The investments referred to in this article may not be suitable for all investors, and if in doubt, an investor should seek advice from a qualified investment adviser.
Full performance can be found on the company or index summary page on the interactive investor website. Simply click on the company's or index name highlighted in the article.