Great British Retirement Survey 2026: Chapter 1
Retirement realities
Chapter 1 of the Great British Retirement Survey unpacks how people are feeling about the prospect of giving up work for good.
Important information: As investment values can go down as well as up, you may not get back all of the money you invest. Currency changes affect international investments, and this can decrease their value in sterling. If you’re unsure if an investment account is right for you, please speak to an authorised financial adviser. Tax treatment depends on your individual circumstances and may be subject to change in the future.
Nearly 4 in 10 retirees are unsure if their savings will last throughout retirement
Uncertainty is a defining feature of retirement today.
Nearly 4 in 10 retirees (39%) are unsure whether their savings will last throughout retirement, with rising living costs and fears of not having saved enough among the biggest concerns.
To make their money go further, many people are working later in life. Nearly 1 in 5 (19%) people aged 66 and over are still working, up from 12% in 2023.
Retirement income is often built from multiple sources, too. Almost half (47%) of retirees rely on the state pension as their main source of income, highlighting the importance of careful planning for later life.
Key findings
- Nearly 1 in 5 people aged 66 and over are still working
- Almost half of retirees rely on the state pension as their main income source
- 4 in 10 retirees are unsure their savings will last
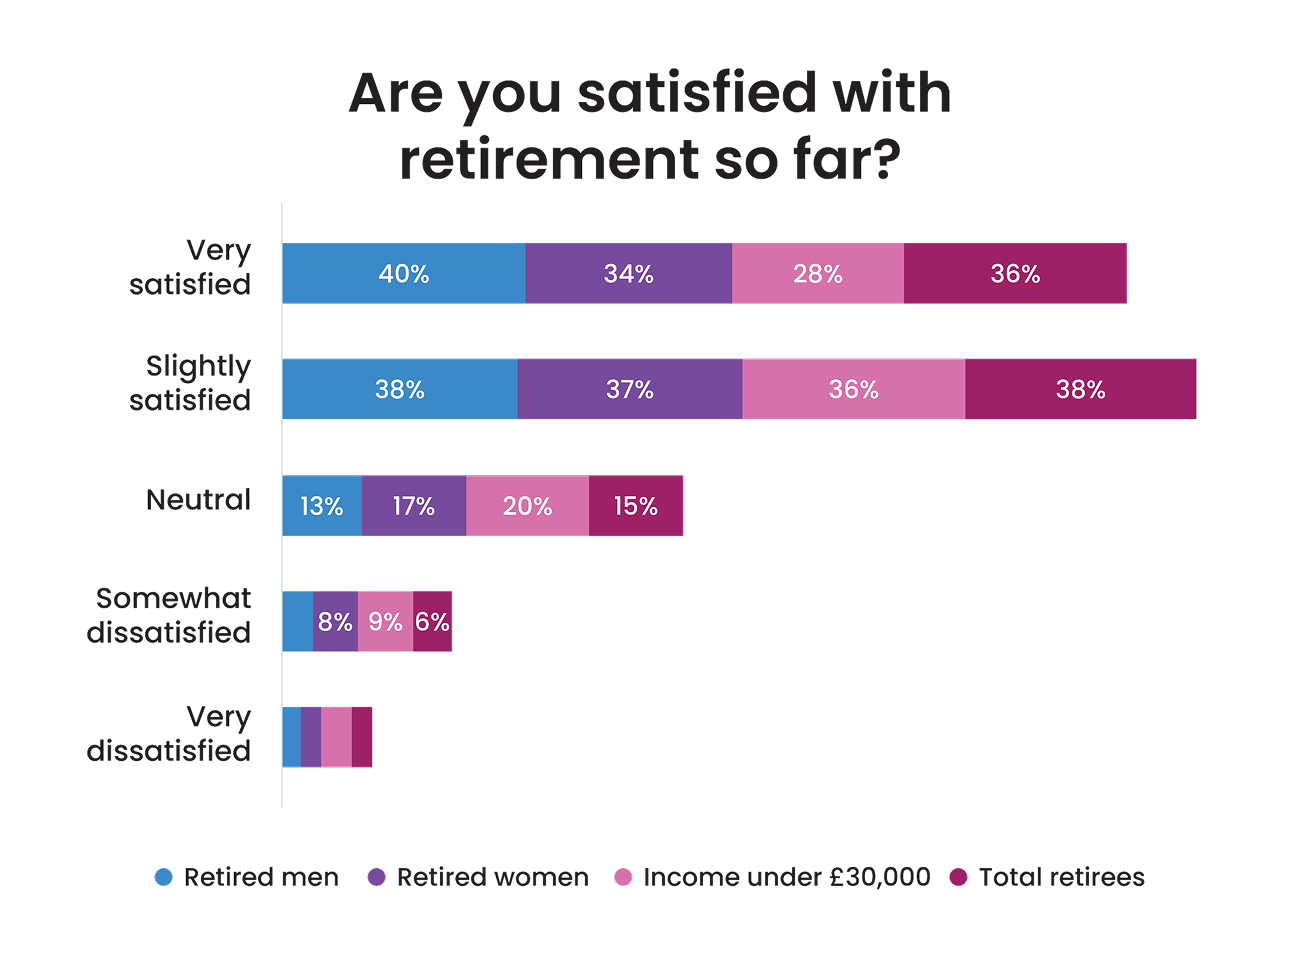
- Despite this, almost three quarters are satisfied with retirement
How are you funding retirement?
Many of us are relying on more than just our pension to fund retirement.

State pension
Nearly 6 in 10 retired women list the state pension as their main income source in retirement. Just 34% of retired men said the same.

Workplace pension
Around 31% say a workplace defined benefit pension is their main source of income. Only 5% of retirees mainly relied on their defined contribution pots.

Other investments
Private pensions, such as SIPPs, are a more common source of retirement income, although both are used by only a small minority of retirees.
Despite pressures, we’re still enjoying retirement
Although future uncertainty persists, the vast majority of retirees are enjoying life.
For many, the biggest reason for their happiness is that they have more freedom and time. Good health, more time to pursue hobbies, and greater financial security are other reasons for enjoying retirement too.
Income, meanwhile, has a small impact on retirement happiness. While retirees with higher incomes are slightly more likely to be satisfied, most people are enjoying retirement regardless of how much they earn.
How to get retirement ready
“While the prospect of retirement might feel unnerving, there are steps you can take to feel in control of your finances.
As retirement can often span several decades, it’s vital for your savings to continue to grow to mitigate the corrosive effects of inflation, which if not kept in check, could see your wealth depleted quicker than needed.
For this reason, often the best approach is to dial investment risk down in retirement rather than remove it from the table. This is a personal decision, and one that’s determined by your individual circumstances and favoured risk appetite – whether that’s more cautious, adventurous, or anything in between.
But, If you’re unsure what action to take, spending the time to sit down with a regulated financial planner.”
ii recommends
People are feeling uncertain when it comes to retirement. Here are some practical changes that could help ease those concerns:
We should commit to fewer changes to both workplace and state pension rules to re-build consumer confidence and public trust in pensions.
We should safeguard the current pension tax system. Rumoured changes, particularly around pension tax-free cash, heightens the risk of savers making knee-jerk decisions with their long-term wealth.
Thinking about a Self-Invested Personal Pension?
Our free Essential Guide to SIPPs has everything you need to know to help you get started. It covers what a SIPP is, how it works and whether it’s right for you.