Shares for the future: the highest quality business I follow
A big upgrade gives this blue-chip stock a perfect score for quality. Analyst Richard Beddard explains why the outlook has improved.
18th September 2026 15:14
by Richard Beddard from interactive investor
For the ninth consecutive year, none of the numbers I use to measure a company's performance and financial strength cause obvious concern at Games Workshop Group (LSE:GAW). It is prodigiously profitable, cash generative and has grown strongly.
- Invest with ii: SIPP Account | Stocks & Shares ISA | See all Investment Accounts
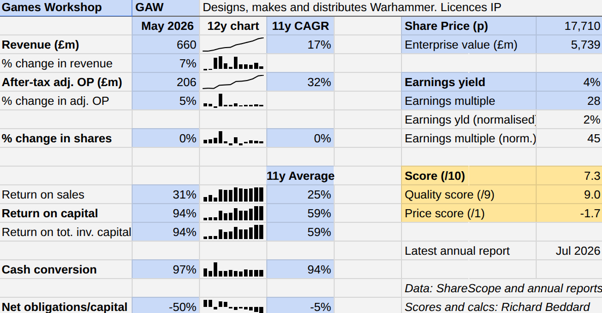
Seven per cent revenue growth and 5% profit growth in the year to May 2026 were well below par, but there is probably nothing to worry about.
A tale of two revenue streams
Games Workshop has two primary revenue streams: core revenue mainly from selling Warhammer fantasy miniatures, model soldiers and armies that hobbyists paint, collect, and play tabletop wargames with, and licensing revenue.
It controls most aspects of “The Hobby” that provides core revenue. Games Workshop has just built its fourth factory in Nottingham, where it makes miniatures. The lore, a vast collection of stories, is propagated in hundreds of novels, rule books and magazines its imprints publish. Five hundred and ninety eight Warhammer stores are hubs for hobbyists, who paint, play and shop there. Many more independent hobby stores stock Warhammer. They and Games Workshop sell Warhammer online.
The lore is Games Workshop's intellectual property. Hobbyists pass it on by word of mouth when they meet up, and virally on social media.
Licensing income is the icing on the cake. Mainly this comes from video game makers, who publish titles based on the lore. Beyond the terms of the licenses and which companies it contracts with, Games Workshop has little control over development and launch schedules. It is a very profitable business, but also lumpy.
- Stockwatch: the case for this income share just got sounder
- Must read weekly preview: Kingfisher, JD Sports, Vistry
For the core, it was business as usual in 2026. Core revenue grew 11%, just below the 12% compound annual growth rate (CAGR) Games Workshop has achieved since 2021. Core operating profit increased 16%, above its five-year CAGR, which is also 12%.
I think this was a good performance because the company did not launch a new edition of either of its two main tabletop games in 2027. New editions change the rules and mechanics of the games and introduce new storylines and characters to keep things interesting for gamers. Naturally, the company creates a buzz and stimulates demand for miniatures.
Video games, films and TV
The big news in recent years has been a film and TV deal signed two years ago with Amazon. This year’s annual report repeats last year's in saying it will take years to bring these adaptations to screens.
Amazon has brought in studio United Artists to make the films and programmes. It will be working with the lead actor, executive producer, Warhammer enthusiast and long-time champion of the project, Henry (Superman) Cavill.
Amazon is also producing an animated series based on Warhammer 40,000, the most popular of Games Workshop’s two imaginary universes. The series is a spin-off of Secret Level, an adult animation series that has already featured Warhammer.
Film and TV projects are mostly jam tomorrow. Most licensing revenue today comes from video games.
Licensing revenue fell 37% in 2026, but in 2025 licensing revenue increased 69%. That year was exceptional due to the launch of Space Marine 2, a massive commercial hit for publisher Focus Entertainment. Space Marines are, perhaps, Warhammer 40,000's most popular faction.
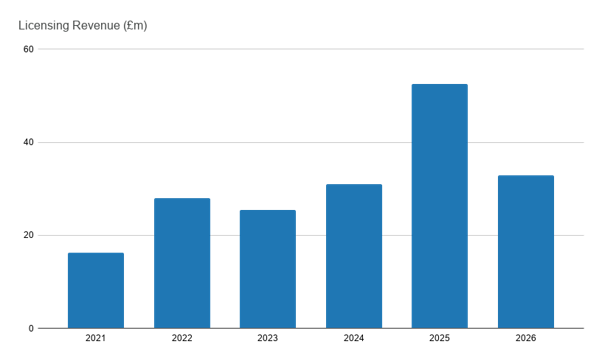
Source: Games Workshop annual reports
In last year's annual report Games Workshop said Space Marine 2 would be a hard act to follow. Nevertheless, revenues from past titles and two new video games meant Games Workshop received more licensing revenue than in any other year in my chart.
Focus has Space Marine 3 in the works, but it is reportedly years away, and four more new video game titles were announced in 2026. A reader has high expectations for Warhammer 40,000: Dawn of War IV, which will be launched in December.
The release of the eleventh edition of Warhammer 40,000 in June 2026 should help the core business to grow again in the current financial year, along with, perhaps, more license income.
Scoring Games Workshop: Self reliance
It is hard not to like Games Workshop. Underneath the three-yearly edition cycles, and the near continuous flow of intermediate releases is a well-oiled manufacturing, design, publishing, and marketing machine.
Kevin Rountree enjoys confessing to occasional, but generally low impact, whoopsies in the annual report. This year it was the operational directors that took the flack. Games Workshop has achieved 102 months of year-on-year growth out of the 120 months in the last financial decade, and it failed to grow in two months in 2026:
"One was in January 2026 due to snow fall at our distribution hub in Memphis (the team were amazing - picking the held sales orders in a few days once the snow was cleared). The other one this year was in May 2026, we missed by £1.5 million, that still hurts. That was due to a poor execution of our plan in the final week of the year. The operational directors were distracted by the detailed planning for the launch of the 11th edition of Warhammer 40,000 in June 2026. But still, no excuses, lessons have been learnt."
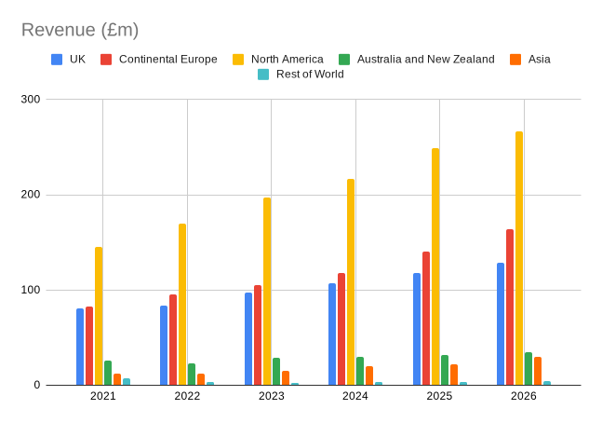
Impressively the growth has been steady across all main regions:
The company's self-reliance extends to staff. The first of six priorities for the new financial year is staff training and recruitment. Games Workshop says it has high retention rates, probably because many employees are hobbyists and there are opportunities to flourish. It says it recruits for attitude over skills. As befitting its aim to recruit internally for all senior roles, its three executives were all promoted to their current posts.
In the past, I have worried that Games Workshop's resistance to outside influence could under certain circumstances be a weakness. My interest in the company was forged under previous management when customers, particularly gamers, were in open rebellion on the internet about ever-more elaborate and pricey models and neglect of the game.
Customers are evidently at the centre of Games Workshop's strategy now, so this year I have belatedly given Games Workshop a perfect score for quality. It is, I think, the highest quality business I follow.
| Games Workshop | GAW | Designs, makes and distributes Warhammer. Licences IP | 16/09/2026 | 7.3/10 |
| How capably has Games Workshop made money? | 3.0 | |||
| For a decade under the leadership of Kevin Rountree, Games Workshop has grown revenue and profit rapidly by expertly satisfying modellers' and wargamers' thirst for new stories and models and simpler more exciting rules. The company has been highly profitable and cash generative. | ||||
| How big are the risks? | 3.0 | |||
| Games Workshop owns intellectual property that has global appeal. It controls most aspects of making, distributing and promoting miniatures. Licence income depends on the capabilities of licensees, but this is the icing on the cake. The biggest risk is managing the many capabilities of a vertically integrated firm. | ||||
| How fair and coherent is its strategy? | 3.0 | |||
| No company is entirely in control of its own destiny, but Warhammer is more so than most, hence its intense staff and customer focus. By providing more Warhammer more often, Games Workshop is growing across all territories.TV and Film should add another major element to license income. | ||||
| How low (high) is the share price compared to normalised profit? | -1.7 | |||
| High. A share price of 17,710p values the enterprise at £5,739 million, about 45 times normalised profit. | ||||
| NB: Bold text indicates factors that reduce the score. Bold and italicised text doubly so. The maximum score is 3 for each criterion except price, which has a maximum of 1 (explained here) | ||||
30 Shares for the future
Here is the ranked list of Decision Engine shares. I review the scores at least once a year, soon after each company has published its annual report. The price scores are calculated using the share price prior to publication.
Generally, I consider shares that score more than 5 out of 10 to be worthy of long-term investment in sizes determined by the ideal holding size (ihs%).
Cohort, Goodwin and Jet2 have published annual reports and are due to be re-scored. Having agreed to a takeover, Advanced Medical Solutions is soon to delist.
| company | description | score | qual | price | ih% | |
| 1 | FW Thorpe | Makes lighting systems for commercial, industrial and public settings | 10.0 | 9.0 | 1.0 | 9.9% |
| 2 | Hollywood Bowl | Operates tenpin bowling centres | 8.7 | 8.0 | 0.7 | 7.3% |
| 3 | Renew | Maintains and improves road, rail, water, and energy infrastructure | 8.1 | 7.5 | 0.6 | 6.3% |
| 4 | Jet2 | Flies people to holiday locations, often on package tours | 8.0 | 7.0 | 1.0 | 6.0% |
| 5 | James Latham | Distributes imported panel products, timber, and laminates | 8.0 | 7.0 | 1.0 | 6.0% |
| 6 | Solid State | Manufactures electronic systems and distributes components | 7.9 | 7.0 | 0.9 | 5.9% |
| 7 | Howden Joinery | Supplies kitchens and joinery to builders and online to DIYers | 7.8 | 7.0 | 0.8 | 5.7% |
| 8 | Anpario | Manufactures natural animal feed additives | 7.8 | 7.0 | 0.8 | 5.6% |
| 9 | Cake Box | Cake shop (Cake Box) and sweet shop (Ambala) franchisor | 7.8 | 7.0 | 0.8 | 5.5% |
| 10 | Porvair | Manufactures filters and laboratory equipment | 7.6 | 8.0 | -0.4 | 5.2% |
| 11 | Cohort | Manufactures/supplies defence tech, training, consultancy | 7.6 | 8.0 | -0.4 | 5.2% |
| 12 | Judges Scientific | Acquires and grows businesses that manufacture scientific instruments | 7.5 | 6.5 | 1.0 | 5.0% |
| 13 | Bunzl | Distributes essential everyday items consumed by businesses | 7.4 | 7.0 | 0.4 | 4.8% |
| 14 | Oxford Instruments | Makes imaging and semiconductor manufacturing systems | 7.4 | 7.0 | 0.4 | 4.7% |
| 15 | Games Workshop | Designs, makes and distributes Warhammer. Licences IP | 7.3 | 9.0 | -1.7 | 4.6% |
| 16 | Volution | Manufacturer of ventilation products | 7.0 | 8.5 | -1.5 | 4.1% |
| 17 | Bloomsbury Publishing | Publishes books and educational resources | 7.0 | 7.5 | -0.5 | 4.1% |
| 18 | Churchill China | Manufactures tableware for restaurants etc. | 7.0 | 6.0 | 1.0 | 4.0% |
| 19 | Auto Trader | Online marketplace for motor vehicles | 7.0 | 6.0 | 1.0 | 3.9% |
| 20 | Quartix | Supplies vehicle tracking systems to small fleets | 6.9 | 7.0 | -0.1 | 3.8% |
| 21 | YouGov | Surveys public opinion and conducts market research online | 6.8 | 6.0 | 0.8 | 3.7% |
| 22 | Macfarlane | Distributes and manufactures protective packaging | 6.5 | 5.5 | 1.0 | 3.0% |
| 23 | Softcat | Sells software and hardware to businesses and public sector | 6.4 | 7.0 | -0.6 | 2.8% |
| 24 | Keystone Law | Operates a network of self-employed lawyers | 6.3 | 7.0 | -0.7 | 2.6% |
| 25 | Advanced Medical Solutions | Manufactures surgical adhesives, sutures and dressings | 6.2 | 6.5 | -0.3 | 2.5% |
| 26 | Focusrite | Designs recording equipment, synthesisers and sound systems | 6.0 | 5.0 | 1.0 | 2.5% |
| 27 | Tristel | Manufactures hospital disinfectant | 6.0 | 8.0 | -2.0 | 2.5% |
| 28 | Goodwin | Casts and machines steel and processes minerals for niche markets | 5.6 | 6.0 | -0.4 | 2.5% |
| 29 | 4Imprint | Customises and distributes promotional goods | 5.6 | 8.0 | -2.4 | 2.5% |
| 30 | Renishaw | Makes tools and systems for manufacturers | 4.7 | 6.5 | -1.8 | 2.5% |
Click on a share’s score to see a breakdown (scores may have changed due to movements in share price). Key: qual is the share’s score out of 9 for the three quality factors (capabilities, risks, and strategy), price is the price score from -3 to +1, and ih% is the suggested ideal holding size as a percentage of the total value of a diversified portfolio.
Richard Beddard is a freelance contributor and not a direct employee of interactive investor.
Richard owns Games Workshop and many shares in the Decision Engine. He weights his portfolio so it owns bigger holdings in the higher-scoring shares.
For more on the Decision Engine and Share Sleuth, please see Richard’s explainer.
Contact Richard Beddard by email: richard@beddard.net or on Twitter: @RichardBeddard
These articles are provided for information purposes only. Occasionally, an opinion about whether to buy or sell a specific investment may be provided by third parties. The content is not intended to be a personal recommendation to buy or sell any financial instrument or product, or to adopt any investment strategy as it is not provided based on an assessment of your investing knowledge and experience, your financial situation or your investment objectives. The value of your investments, and the income derived from them, may go down as well as up. You may not get back all the money that you invest. The investments referred to in this article may not be suitable for all investors, and if in doubt, an investor should seek advice from a qualified investment adviser.
Full performance can be found on the company or index summary page on the interactive investor website. Simply click on the company's or index name highlighted in the article.
Disclosure
We use a combination of fundamental and technical analysis in forming our view as to the valuation and prospects of an investment. Where relevant we have set out those particular matters we think are important in the above article, but further detail can be found here.
Please note that our article on this investment should not be considered to be a regular publication.
Details of all recommendations issued by ii during the previous 12-month period can be found here.
ii adheres to a strict code of conduct. Contributors may hold shares or have other interests in companies included in these portfolios, which could create a conflict of interests. Contributors intending to write about any financial instruments in which they have an interest are required to disclose such interest to ii and in the article itself. ii will at all times consider whether such interest impairs the objectivity of the recommendation.
In addition, individuals involved in the production of investment articles are subject to a personal account dealing restriction, which prevents them from placing a transaction in the specified instrument(s) for a period before and for five working days after such publication. This is to avoid personal interests conflicting with the interests of the recipients of those investment articles.