Shares for the future: hidden risks at this stock prey on my mind
This complex business will soon become much simpler, but there are a number of uncertainties which concern analyst Richard Beddard.
25th September 2026 15:11
by Richard Beddard from interactive investor
Usually, my articles include a table showing the performance of the company I am scoring. This year I cannot do that, because Goodwin (LSE:GDWN) has sold most of the larger of its two long-standing divisions.
Sale of the century
Because negotiations were at an advanced stage when Goodwin published its annual report, the Mechanical Engineering division was treated as a discontinued operation. The reported results for the continuing operation are not comparable to previous years because it will be so much smaller.
- Our Services: SIPP Account | Stocks & Shares ISA | See all Investment Accounts
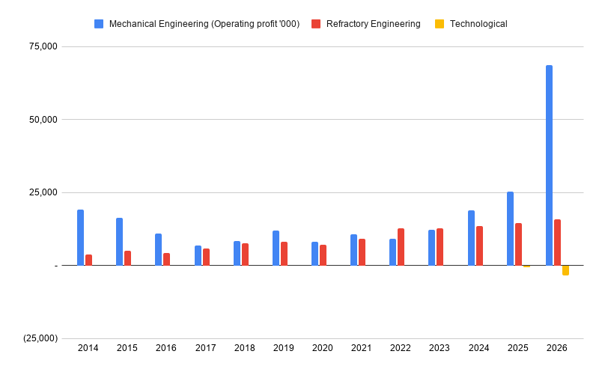
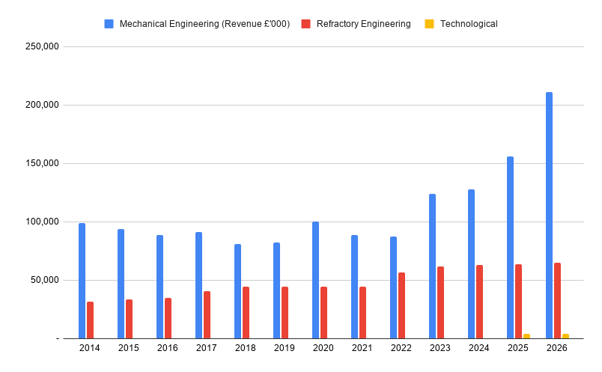
However, Goodwin benefited from ownership of Mechanical Engineering for the whole of the year to April 2026 (and will for most of 2027). Revenue and profit figures for the discontinued operation show the improvement in 2026 (blue bars in the chart below) was, as had been promised, phenomenal.
Source: Goodwin annual reports
Historically, Mechanical Engineering has contributed most of Goodwin's revenue. Goodwin Steel Castings is the company's oldest business, founded in 1883.
During the past decade, Goodwin pivoted from previously lucrative but weak oil and gas markets to the nuclear and defence industries, principally in the US. This has required it to invest heavily in its foundry, and develop new relationships with demanding customers, which has dragged on profitability.
Over the last three years, though, Mechanical Engineering has re-established itself as the indisputable profit centre of the group. It has also been helped by a return to profit of a subsidiary that makes radar systems.
Source: Goodwin annual reports
It seemed like Goodwin had positioned itself to profit for decades from long-term contracts to supply the US and UK naval frigate and submarine programmes and nuclear waste containers in an increasingly hostile and energy hungry world. Instead, it has accepted a £1.1 billion offer for the business from US private equity firm Cerberus.
Why Goodwin has disposed of its biggest and most profitable business is something of a mystery. The company says as part of Cerberus, Mechanical Engineering will benefit from investment and leadership experienced in the defence sector. It wants to focus on the second division, Refractory Engineering and a new division, Technologies.
Mechanical Engineering will contribute revenue for most of financial year 2027. After that Goodwin will return a substantial portion of the £1.1 billion sale proceeds to shareholders and retain some in the remaining business so it can operate on a zero-net debt basis.
- AIM’s best companies of 2026: shortlist revealed
- Stockwatch: why it’s time to pay serious attention to this share
Since Goodwin's market capitalisation is slightly lower than the £1.1 billion headline price for Mechanical Engineering, either traders are discounting risk associated with the deal, or they think the rest of the business is worthless.
There is risk. Completion is some distance away, subject to approval by various authorities, and the £1.1 billion price is at the same time "approximate", "maximum" and "subject to customary closing adjustments".
The remaining business is not worthless. It is small but consists of a profitable and growing core and a promising but loss-making startup.
Future Goodwin
Goodwin's involvement in Refractory Engineering began in 1965, when it acquired Goodwin Refractory Services (GRS). GRS and its manufacturing and sales offshoots in India, China and Thailand make investment casting (moulding) powders, waxes and rubbers used in lost wax casting. This is a process used to manufacture jewellery and tyres.
Since its main rival Kerr ceased production in 2018, Goodwin has described GRS as the global market leader in investment casting powders.
Due to the high price of gold and silver, GRS reports that jewellery buyers are moving downmarket from precious jewellery to "wear once" items. Goodwin benefits because the same quantity of casting powder is required whether jewellery is cast in brass or gold, and the volumes are much higher. To meet demand, it is planning to open another powder production facility in China.
Refractory Engineering also includes Hoben International and Dupré Minerals. Hoben quarries and processes minerals including cristobalite, the primary raw material of its casting powders, and ground silica, also an ingredient. Dupré processes another mineral, vermiculite, which can withstand very high temperatures. It is used in insulation, brake linings and technical textiles.
- Anthropic IPO: what UK investors need to know
- 20 hottest tech stocks of the week: Strategy, Meta, Micron Tech
Refractory Engineering has similar favourable characteristics to the Mechanical Engineering division: vertical integration and niche technical expertise. During the Mechanical Engineering division's reconfiguration, Refractory Engineering kept the group's results respectable.
Since 2017, Refractory Engineering has grown revenue at a compound annual growth rate (CAGR) of 8%, and operating profit at 17% CAGR. Profit margin has improved from 15% to 24%. Operating profit in 2026 was nearly £16 million. If you were to apply a multiple of 15 times profit, the business might be worth £240 million.
After the sale of Mechanical Engineering, Goodwin says it will put particular emphasis on accelerating the commercialisation of AVD Fire and another business, Duvelco. Duvelco made a £3.5 million loss in 2026.
Along with Internet Central, an internet service provider that was last mentioned outside the notes in a Goodwin annual report in 2007, Duvelco forms the new Technologies division. Both businesses are part of Mechanical Engineering. They are now in the process of being carved out.
Duvelco makes Ducoya, a novel polyamide resin, which is a high-performance plastic that can be moulded into parts for planes, cars, and semiconductor manufacturing equipment where properties like heat and chemical resistance are important.
In development since 2020, last year Duvelco was granted a patent on a "process step" and also completed the factory in which Ducoya will be produced.
In that year's annual report, Goodwin stated its belief that Duvelco would be the "largest and most profitable division in years to come." It is, of course, selling its largest and currently most profitable business, so the bar has been lowered.
- Why Raspberry Pi shares just surged 20%
- Sign up to our free newsletter for investment ideas, latest news and award-winning analysis
This year's annual report revealed teething problems. Duvelco has experienced production problems of a "mechanical, not fundamental" nature. The distribution of samples to potential customers has been delayed and so too has "meaningful revenue".
The company does not believe this is a long-term risk, but it has de-risked another aspect of the project. Duvelco has outsourced the compression moulding of parts to a third party rather than make pre-formed shapes and parts itself as it had initially intended.
Snags, and strategic adjustments, are unsettling, but may be par for the course considering Ducoya is novel and historically Goodwin has sometimes taken longer than it initially anticipates to deliver ambitious promises.
Scoring Goodwin: Hidden risk?
Goodwin is a complex business, and the sale of Mechanical Engineering simplifies it. That makes the remaining business attractive to me. But the uncertainty of the disposal, the size of the remaining business, and the Goodwin family's 54% shareholding concerns me.
The family will be major beneficiaries of the sale. If the company seeks to return the cash raised to shareholders by tendering for shares, its grip could tighten. Flush with cash, it would probably have the means to take the company private and most of the votes it would need to do it. Given its firm belief in the prospects of Duvelco and AVD, why wouldn't it?
This is speculation. I do not know the family's intentions. But if delisting is the end-game it would turn a long-term investment into a short-term trade, and that possibility preys on my mind.
| Goodwin | GDWN | Casts and machines steel and processes minerals for niche markets | 23/09/2026 | 5.5/10 |
| How capably has Goodwin made money? | 2.0 | |||
| Over the last nine years, Goodwin has grown revenue modestly and profit more strongly while building capacity and capabilities in niche markets. The sale of Mechanical Engineering shrinks the business dramatically, reducing the relevance of its financial history and increasing the significance of moonshot Duvelco. | ||||
| How big are the risks? | 2.0 | |||
| To grow beyond its niches Goodwin must establish new products and businesses, which can take longer than expected and may result in failure.It will be a simpler net-debt free business after the sale, focused on commercialising two novel new products: Ducoya and AVD Fire. | ||||
| How fair and coherent is its strategy? | 2.0 | |||
| Goodwin invests for the long-term in global businesses too small to attract competition from large multinationals. I have always regarded the involvement of the Goodwin family as positive, but their majority stake worries me now. I fear it might take the company privateafter the sale. | ||||
| How low (high) is the share price compared to profit? | -0.5 | |||
| High. A share price of 13,660p values the enterprise at £1,050 million, about 20 times 2026 operating profit (after-tax). | ||||
| NB: Bold text indicates factors that reduce the score. Bold and italicised text doubly so. The maximum score is 3 for each criterion except price, which has a maximum of 1 (explained here) | ||||
30 Shares for the future
Here is the ranked list of Decision Engine shares. I review the scores at least once a year, soon after each company has published its annual report. The price scores are calculated using the share price prior to publication.
Generally, I consider shares that score more than 5 out of 10 to be worthy of long-term investment in sizes determined by the ideal holding size (ihs%).
Cohort (LSE:CHRT) and Jet2 Ordinary Shares (LSE:JET2) have published annual reports and are due to be re-scored. Having agreed to a takeover, Advanced Medical Solutions Group (LSE:AMS) is soon to delist.
| company | description | score | qual | price | ih% | |
| 1 | FW Thorpe | Makes lighting systems for commercial, industrial and public settings | 9.9 | 9.0 | 0.9 | 9.8% |
| 2 | Hollywood Bowl | Operates tenpin bowling centres | 8.6 | 8.0 | 0.6 | 7.3% |
| 3 | Jet2 | Flies people to holiday locations, often on package tours | 8.0 | 7.0 | 1.0 | 6.0% |
| 4 | James Latham | Distributes imported panel products, timber, and laminates | 8.0 | 7.0 | 1.0 | 6.0% |
| 5 | Solid State | Manufactures electronic systems and distributes components | 8.0 | 7.0 | 1.0 | 5.9% |
| 6 | Renew | Maintains and improves road, rail, water, and energy infrastructure | 7.9 | 7.5 | 0.4 | 5.9% |
| 7 | Howden Joinery | Supplies kitchens and joinery to builders and online to DIYers | 7.8 | 7.0 | 0.8 | 5.6% |
| 8 | Cake Box | Cake shop (Cake Box) and sweet shop (Ambala) franchisor | 7.8 | 7.0 | 0.8 | 5.5% |
| 9 | Anpario | Manufactures natural animal feed additives | 7.7 | 7.0 | 0.7 | 5.3% |
| 10 | Judges Scientific | Acquires and grows businesses that manufacture scientific instruments | 7.5 | 6.5 | 1.0 | 5.0% |
| 11 | Cohort | Manufactures/supplies defence tech, training, consultancy | 7.5 | 8.0 | -0.5 | 4.9% |
| 12 | Porvair | Manufactures filters and laboratory equipment | 7.4 | 8.0 | -0.6 | 4.8% |
| 13 | Bunzl | Distributes essential everyday items consumed by businesses | 7.3 | 7.0 | 0.3 | 4.6% |
| 14 | Games Workshop | Designs, makes and distributes Warhammer. Licences IP | 7.3 | 9.0 | -1.7 | 4.6% |
| 15 | Quartix | Supplies vehicle tracking systems to small fleets | 7.1 | 7.0 | 0.1 | 4.2% |
| 16 | Bloomsbury Publishing | Publishes books and educational resources | 7.1 | 7.5 | -0.4 | 4.1% |
| 17 | Churchill China | Manufactures tableware for restaurants etc. | 7.0 | 6.0 | 1.0 | 4.0% |
| 18 | Auto Trader | Online marketplace for motor vehicles | 7.0 | 6.0 | 1.0 | 3.9% |
| 19 | Oxford Instruments | Makes imaging and semiconductor manufacturing systems | 6.9 | 7.0 | -0.1 | 3.9% |
| 20 | Volution | Manufacturer of ventilation products | 6.9 | 8.5 | -1.6 | 3.8% |
| 21 | YouGov | Surveys public opinion and conducts market research online | 6.8 | 6.0 | 0.8 | 3.7% |
| 22 | Macfarlane | Distributes and manufactures protective packaging | 6.5 | 5.5 | 1.0 | 3.0% |
| 23 | Keystone Law | Operates a network of self-employed lawyers | 6.3 | 7.0 | -0.7 | 2.7% |
| 24 | Softcat | Sells software and hardware to businesses and public sector | 6.3 | 7.0 | -0.7 | 2.6% |
| 25 | Advanced Medical Solutions | Manufactures surgical adhesives, sutures and dressings | 6.2 | 6.5 | -0.3 | 2.5% |
| 26 | Focusrite | Designs recording equipment, synthesisers and sound systems | 6.0 | 5.0 | 1.0 | 2.5% |
| 27 | Tristel | Manufactures hospital disinfectant | 5.9 | 8.0 | -2.1 | 2.5% |
| 28 | 4Imprint | Customises and distributes promotional goods | 5.5 | 8.0 | -2.5 | 2.5% |
| 29 | Goodwin | Casts and machines steel and processes minerals for niche markets | 5.5 | 6.0 | -0.5 | 2.5% |
| 30 | Renishaw | Makes tools and systems for manufacturers | 4.4 | 6.5 | -2.1 | 2.5% |
Click on a share’s score to see a breakdown (scores may have changed due to movements in share price). Key: qual is the share’s score out of 9 for the three quality factors (capabilities, risks, and strategy), price is the price score from -3 to +1, and ih% is the suggested ideal holding size as a percentage of the total value of a diversified portfolio.
Richard Beddard is a freelance contributor and not a direct employee of interactive investor.
Richard owns Goodwin and many shares in the Decision Engine. He weights his portfolio so it owns bigger holdings in the higher-scoring shares.
For more on the Decision Engine and Share Sleuth, please see Richard’s explainer.
Contact Richard Beddard by email: richard@beddard.net or on Twitter: @RichardBeddard
AIM stocks tend to be volatile high-risk/high-reward investments and are intended for people with an appropriate degree of equity trading knowledge and experience.
Disclosure
We use a combination of fundamental and technical analysis in forming our view as to the valuation and prospects of an investment. Where relevant we have set out those particular matters we think are important in the above article, but further detail can be found here.
Please note that our article on this investment should not be considered to be a regular publication.
Details of all recommendations issued by ii during the previous 12-month period can be found here.
ii adheres to a strict code of conduct. Contributors may hold shares or have other interests in companies included in these portfolios, which could create a conflict of interests. Contributors intending to write about any financial instruments in which they have an interest are required to disclose such interest to ii and in the article itself. ii will at all times consider whether such interest impairs the objectivity of the recommendation.
In addition, individuals involved in the production of investment articles are subject to a personal account dealing restriction, which prevents them from placing a transaction in the specified instrument(s) for a period before and for five working days after such publication. This is to avoid personal interests conflicting with the interests of the recipients of those investment articles.
These articles are provided for information purposes only. Occasionally, an opinion about whether to buy or sell a specific investment may be provided by third parties. The content is not intended to be a personal recommendation to buy or sell any financial instrument or product, or to adopt any investment strategy as it is not provided based on an assessment of your investing knowledge and experience, your financial situation or your investment objectives. The value of your investments, and the income derived from them, may go down as well as up. You may not get back all the money that you invest. The investments referred to in this article may not be suitable for all investors, and if in doubt, an investor should seek advice from a qualified investment adviser.
Full performance can be found on the company or index summary page on the interactive investor website. Simply click on the company's or index name highlighted in the article.