Shares for the future: why this stock remains my number one
Analyst Richard Beddard thinks this share price is currently well below fair value and that the company, which heads his 30-strong Decision Engine, should prosper over the long term.
30th October 2026 15:00
by Richard Beddard from interactive investor
Three fractional contractions in revenue in three years may be nothing to worry about but, as an investor that focuses on risks, I haven't got anything else to hang my concerns on at Thorpe (F W) (LSE:TFW).
- Invest with ii: SIPP Account | Stocks & Shares ISA | See all Investment Accounts
Not such a good year
FW Thorpe makes industrial, commercial, road and tunnel lighting systems. It is dependent on the investment decisions of customers whose willingness to build or refurbish factories, shops, schools, hospitals and infrastructure depends on how prosperous they are. Profit, though, has declined by more than 1% only once in the last 12 years.
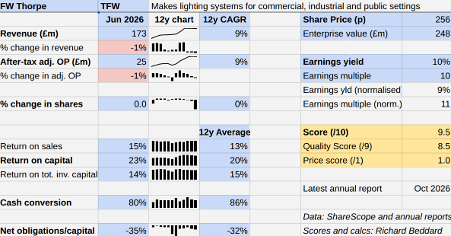
That was in 2020, the first year of the pandemic, when adjusted operating profit fell 26%. Otherwise, good years have been very good. Bad years, not so bad. The year to June 2026 was, like the year before it, a not so bad year.
Over the last 12 years, FW Thorpe has grown revenue at a compound annual growth rate (CAGR) of 9%, and adjusted profit by 9% too.
In 2026, Thorpe’s beating heart, Thorlux, skipped a beat. Redditch based Thorlux is the original business, now 90 years old. It makes a wide range of lighting systems and brings in more revenue than all the other subsidiaries combined.
Thorlux faced tough comparatives. 2025 was a record year, and despite a 3% decline in revenue, 2026 was its second best. The subsidiary’s German outpost SchahlLED, which mostly supplies warehouses, is mired in a prolonged industrial recession there. Revenue has declined every year since FW Thorpe acquired it in 2022.
Thorpe’s other subsidiaries are more specialised. Lightronics, an outdoor lighting specialist based in the Netherlands, also suffered a contraction in exports to Germany and heightened competition in a weak home market.
Zemper, a Spanish manufacturer of emergency lighting, saved the company from an uncharacteristically severe contraction. It increased profit by over 40% and overtook Lightronics to become the group’s second-biggest contributor to revenue and profit.
Most of Thorlux’s smaller subsidiaries also contributed more revenue. Famostar, a Dutch emergency lighting company, grew. So did British subsidiary Solite, which makes ingress-protected lighting systems for laboratories and clean rooms. It has also won a contract to supply a Scottish prison.
- Wild’s Winter Portfolios 2026: winning stocks revealed
- Sign up to our free newsletter for investment ideas, latest news and award-winning analysis
Having renewed the TRT sales team last year, the intermittently profitable road and tunnel division returned to profit. News that TRT is shipping the largest order in the group’s history over the next two years, may be vindication for the new team. It may also mean TRT stays profitable, at least for a while.
The annual report does not dwell on Ratio EV, a loss-making electric vehicle (EV) charging joint venture. Losses have reduced though, and it was profitable in the second half of the financial year.
The conditions FW Thorpe is experiencing at its contracting subsidiaries, weak demand, competitive pricing and higher employee costs, are evident across the group. This is because it earns almost all its revenue in economically troubled Western Europe.
Procurement savings have protected margins, but they are becoming harder to come by so FW Thorpe needs to get Lightronics and SchahlLED growing again.
At Lightronics it has appointed a new commercial director, and it is introducing products and innovations from Thorlux and TRT.
At SchahlLED it is employing more sales executives and diversifying into commercial markets, healthcare and education, sectors the Thorlux mothership has long served in the UK.
In the annual report, FW Thorpe says the group’s performance in the first three months of the year to June 2027 was marginally below the same period in 2026, but orders were higher.
If the company is to endure another challenging year, at least it is on a typically sound financial footing. At the end of the year, FW Thorpe was £35 million in the black. The ratio of net excess cash to operating capital was 32%. Return on capital of 23% was slightly above the historical average.
Product
FW Thorpe has scaled an attractive niche by acquiring emergency lighting specialists Zemper and Famostar in the last decade. Combined with the emergency lighting businesses of Thorlux and Philip Payne, a small UK subsidiary, these products, required by safety regulations, contributed 45% of revenue in 2026.
Acquisitions have increased the complexity of the group, though. The company admits it can be challenging to generate efficiencies by sharing know-how and procuring together, but it reports progress on both fronts. It also reports a set-back in its goal of cross-selling products.
Starting with the setback, Philip Payne has largely failed to sell Zemper’s technologically advanced systems, because they address a different market.
Zemper is currently supplying a large European airport with its new ALIOTH system, which uses a dynamic TFT display that can update escape-route instructions when, for example, a route is blocked. Philip Payne’s reputation is founded on bespoke systems that match the decor of the institution, often at low volumes. It has kitted out the Royal Albert Hall.
FW Thorpe’s most successful technical synergy has been the implementation of Thorlux’s SmartScan wireless management system across most of the group’s products. Now 10 years old and about to enter its third generation, SmartScan improves energy efficiency by adjusting lighting according to levels of movement and natural lighting.
The transition from old-school incandescent lighting to LED systems started over 20 years ago, driven by the lower energy requirements of the newer technology. Today, 99% of Thorpe’s sales are LED and FW Thorpe has shifted its attention to other ways controls and sensors can add value.
SmartScan self-tests emergency lighting systems, to demonstrate compliance with fire safety codes. For many businesses compliance is a costly manual process.
SmartScan can also test air quality and control colour temperature. An optional analytics software package incorporates other aspects of building performance, like energy consumption.
These innovations are prior examples of FW Thorpe’s ‘product-led’ strategy.
This year’s annual report showcases Vionis, a lighting system that integrates continuous low-level antimicrobial disinfection safely in occupied spaces. It is being incorporated into Thorlux and Solite light fixtures, controlled by SmartScan.
Purpose
The company also describes itself as purposeful. Zemper and Thorlux are patenting luminaires (light fixtures) made from cork, which will be launched later this year under the Corkia brand name. They are cheaper and more sustainable than wooden and plastic luminaires.
It has long targeted environmental sustainability, having achieved carbon neutrality in its own operations in 2012. This policy is not greenwashing, it is an offshoot of FW Thorpe’s broad long-term ethos.
Long-termism is evident in the business model. Designed to be reliable and efficient, the company says it’s the lowest long-term cost of ownership. FW Thorpe’s financial strength means it will be around to provide spares and upgrades when needed.
To help architects, designers, contractors and end customers choose, install and maintain their lighting, FW Thorpe provides survey, design, and lifetime support services, which generates repeat custom. Customers choose FW Thorpe, it says, for peace of mind.
People
The third “P” in Thorlux’s “growth mindset” is People. Ordinarily, it is actually the first in the string of P’s that populates its annual report: people, product, purpose. Such alliterations would be glib if the company’s actions and results did not bear them out.
FW Thorpe says it treats staff like family. It takes pride in its training programmes and in paying more than the national minimum wage. As that number inflates, the company maintains differentials so pay looks generous at every level.
- Stockwatch: buy Alphabet’s crash or chase Microsoft’s momentum?
- The two stocks paying biggest FTSE 100 dividends in November
One group of people, the founding family, deserves consideration. Brothers Ian and Andrew, both former executives and now non-executives, and other family members own about 50% of the shares.
The family’s presence on the share register has been an unalloyed positive, probably since FW Thorpe listed in 1969. But there is the small but not completely discountable risk that they might use their majority in a way that undermines the interests of minority long-term shareholders, for example by taking the company private at a low price.
Delisting risk is on my mind because I think the share price is currently well below fair value, and the board agrees. FW Thorpe bought back shares worth £11.5 million in 2026 specifically to take advantage.
To my mind, the benefit of a stable and benign majority shareholder, outweighs the remote but nasty thought it might turn predatory.
Scoring FW Thorpe: the long game
FW Thorpe has contracted, albeit minutely, in recent years and that has impacted its score. Arbitrarily, I deem 10% compound annual growth over the long-term sufficient to deem a business fast growing. At 9% on both counts, it just fails to make the cut, and I have deducted half a point for the near miss.
| FW Thorpe | TFW | Makes lighting systems for commercial, industrial and public settings | 29/10/2026 | 9.5/10 |
| How capably has FW Thorpe made money? | 2.5 | |||
| Under consistent management, FW Thorpe has profited from the adoption of LED lighting by innovating more capable systems supported by planning, installation and after sales service, and acquiring European subsidiaries. It has achieved high Return on Capital and grown profit at 9% CAGR over the last 12 years. | ||||
| How big are the risks? | 3.0 | |||
| FW Thorpe owns its own facilities and earns strong cash flows. It has surplus cash. Customers cut capital spending in recessions, but Thorpe’s diversity has helped weather them. The company’s expansion into Europe by acquisition has increased its complexity but enhanced its growth potential. | ||||
| How fair and coherent is its strategy? | 3.0 | |||
| The company differentiates its products from cheap imports through innovation, quality, and support. This increases the functionality of lighting, reduces the lifetime and environmental cost, and helps retain customers. It pays employees well and treats them like family. The controlling Thorpe family have been good stewards. | ||||
| How low (high) is the share price compared to normalised profit? | 1.0 | |||
| Low. A share price of 256p values the enterprise at £248 million, about 11 times normalised profit. | ||||
| NB: Bold text indicates factors that reduce the score. Bold and italicised text doubly so. The maximum score is 3 for each criterion except price, which has a maximum of 1 (explained here) | ||||
| Previous score (November 2025): 9.8 | ||||
I think FW Thorpe should prosper over the long term because of its ethos, and because of the diversity of its product range. It is also reassuring that its biggest niche, compliant emergency lighting, is not discretionary.
The company still earns more than 50% of revenue in the UK, but acquisitions in the last decade or so have given it the opportunity to grow in a much bigger market.
It is introducing more of the group’s products where it already has a sales presence, opening offices in new territories, and it may acquire more businesses.
It will take time to establish itself like it has here, but FW Thorpe is all about the long game.
30 Shares for the future
Here is the ranked list of Decision Engine shares. I review the scores at least once a year, soon after each company has published its annual report. The price scores are calculated using the share price prior to publication.
Generally, I consider shares that score more than 5 out of 10 to be worthy of long-term investment in sizes determined by the ideal holding size (ihs%).
Renishaw (LSE:RSW), Volution Group (LSE:FAN) and Softcat (LSE:SCT) have published annual reports and are due to be re-scored.
| company | description | score | qual | price | ih% | |
| 1 | FW Thorpe | Makes lighting systems for commercial, industrial and public settings | 9.5 | 8.5 | 1.0 | 8.9% |
| 2 | Hollywood Bowl | Operates tenpin bowling centres | 8.5 | 8.0 | 0.5 | 6.9% |
| 3 | James Latham | Distributes imported panel products, timber, and laminates | 8.0 | 7.0 | 1.0 | 6.0% |
| 4 | Solid State | Manufactures electronic systems and distributes components | 8.0 | 7.0 | 1.0 | 5.9% |
| 5 | Cake Box | Cake shop (Cake Box) and sweet shop (Ambala) franchisor | 7.8 | 7.0 | 0.8 | 5.7% |
| 6 | Howden Joinery | Supplies kitchens and joinery to builders and online to DIYers | 7.8 | 7.0 | 0.8 | 5.5% |
| 7 | Porvair | Manufactures filters and laboratory equipment | 7.5 | 8.0 | -0.5 | 5.0% |
| 8 | Anpario | Manufactures natural animal feed additives | 7.5 | 7.0 | 0.5 | 5.0% |
| 9 | Renew | Maintains and improves road, rail, water, and energy infrastructure | 7.5 | 7.5 | 0.0 | 4.9% |
| 10 | Games Workshop | Designs, makes and distributes Warhammer. Licences IP | 7.4 | 9.0 | -1.6 | 4.8% |
| 11 | Oxford Instruments | Makes imaging and semiconductor manufacturing systems | 7.3 | 7.0 | 0.3 | 4.6% |
| 12 | Bunzl | Distributes essential everyday items consumed by businesses | 7.2 | 7.0 | 0.2 | 4.4% |
| 13 | Quartix | Supplies vehicle tracking systems to small fleets | 7.1 | 7.0 | 0.1 | 4.3% |
| 14 | Churchill China | Manufactures tableware for restaurants etc. | 7.0 | 6.0 | 1.0 | 4.0% |
| 15 | Jet2 | Flies people to holiday locations, often on package tours | 7.0 | 6.0 | 1.0 | 4.0% |
| 16 | Judges Scientific | Acquires and grows businesses that manufacture scientific instruments | 7.0 | 6.0 | 1.0 | 4.0% |
| 17 | Auto Trader | Online marketplace for motor vehicles | 6.9 | 6.0 | 0.9 | 3.9% |
| 18 | Volution | Manufacturer of ventilation products | 6.9 | 8.5 | -1.6 | 3.8% |
| 19 | Bloomsbury Publishing | Publishes books and educational resources | 6.9 | 7.5 | -0.6 | 3.8% |
| 20 | YouGov | Surveys public opinion and conducts market research online | 6.8 | 6.0 | 0.8 | 3.6% |
| 21 | Macfarlane | Distributes and manufactures protective packaging | 6.5 | 5.5 | 1.0 | 2.9% |
| 22 | Advanced Medical Solutions | Manufactures surgical adhesives, sutures and dressings | 6.2 | 6.5 | -0.3 | 2.5% |
| 23 | Cohort | Manufactures/supplies defence tech, training, consultancy | 6.1 | 7.5 | -1.4 | 2.5% |
| 24 | Keystone Law | Operates a network of self-employed lawyers | 6.0 | 7.0 | -1.0 | 2.5% |
| 25 | Focusrite | Designs recording equipment, synthesisers and sound systems | 6.0 | 5.0 | 1.0 | 2.5% |
| 26 | Softcat | Sells software and hardware to businesses and public sector | 6.0 | 6.5 | -0.5 | 2.5% |
| 27 | Tristel | Manufactures hospital disinfectant | 5.9 | 8.0 | -2.1 | 2.5% |
| 28 | 4Imprint | Customises and distributes promotional goods | 5.5 | 8.0 | -2.5 | 2.5% |
| 29 | Goodwin | Casts and machines steel and processes minerals for niche markets | 5.1 | 6.0 | -0.9 | 2.5% |
| 30 | Renishaw | Makes tools and systems for manufacturers | 4.4 | 6.5 | -2.1 | 2.5% |
Click on a share's score to see a breakdown (scores may have changed due to movements in share price). Key: qual is the share’s score out of 9 for the three quality factors (capabilities, risks, and strategy), price is the price score from -3 to +1, and ih% is the suggested ideal holding size as a percentage of the total value of a diversified portfolio.
Richard Beddard is a freelance contributor and not a direct employee of interactive investor.
Richard owns FW Thorpe and many shares in the Decision Engine. He weights his portfolio so it owns bigger holdings in the higher-scoring shares.
For more on the Decision Engine and Share Sleuth, please see Richard’s explainer.
Contact Richard Beddard by email: richard@beddard.net or on Twitter: @RichardBeddard
AIM stocks tend to be volatile high-risk/high-reward investments and are intended for people with an appropriate degree of equity trading knowledge and experience.
These articles are provided for information purposes only. Occasionally, an opinion about whether to buy or sell a specific investment may be provided by third parties. The content is not intended to be a personal recommendation to buy or sell any financial instrument or product, or to adopt any investment strategy as it is not provided based on an assessment of your investing knowledge and experience, your financial situation or your investment objectives. The value of your investments, and the income derived from them, may go down as well as up. You may not get back all the money that you invest. The investments referred to in this article may not be suitable for all investors, and if in doubt, an investor should seek advice from a qualified investment adviser.
Full performance can be found on the company or index summary page on the interactive investor website. Simply click on the company's or index name highlighted in the article.
Disclosure
We use a combination of fundamental and technical analysis in forming our view as to the valuation and prospects of an investment. Where relevant we have set out those particular matters we think are important in the above article, but further detail can be found here.
Please note that our article on this investment should not be considered to be a regular publication.
Details of all recommendations issued by ii during the previous 12-month period can be found here.
ii adheres to a strict code of conduct. Contributors may hold shares or have other interests in companies included in these portfolios, which could create a conflict of interests. Contributors intending to write about any financial instruments in which they have an interest are required to disclose such interest to ii and in the article itself. ii will at all times consider whether such interest impairs the objectivity of the recommendation.
In addition, individuals involved in the production of investment articles are subject to a personal account dealing restriction, which prevents them from placing a transaction in the specified instrument(s) for a period before and for five working days after such publication. This is to avoid personal interests conflicting with the interests of the recipients of those investment articles.