FTSE 100 shares round-up: Nick Train has plenty to smile about
After coming under fire for some big losses among core holdings, this high-profile manager is having a much better month. City writer Graeme Evans explains why.
22nd October 2026 13:31
by Graeme Evans from interactive investor
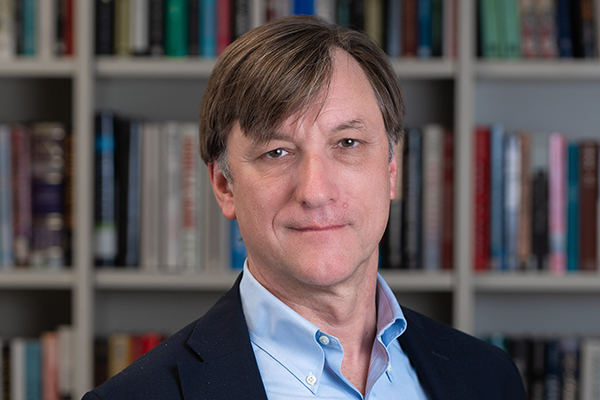
Nick Train’s view of London Stock Exchange Group (LSE:LSEG) and RELX (LSE:REL) as beneficiaries rather than victims of AI today gained support after the FTSE 100 stocks consolidated October’s strong run.
LSEG, which is the third-largest holding of Train’s Finsbury Growth & Income Ord (LSE:FGT) Trust, rose 326p to 9,116p after the financial data and markets business bolstered its full-year guidance and announced a major US acquisition.
The shares have rallied by 12% since the start of this month, while data and analytics services business RELX is 18% higher following a slight dip in the wake of today’s in-line update.
- Invest with ii: Top UK Shares | Share Tips & Ideas | Open a Trading Account
Both stocks are back where they started the year, having been the subject of de-ratings due to worries over the impact of disruption from AI tools launched by Anthropic and others.
RELX, which accounts for 10% of the Finsbury portfolio, fell as far as February’s 2,013p before October’s rebound left shares at today’s opening price of 2,973p.
This year’s sell-off took place even though RELX is arguably the UK’s leading quoted AI company, having launched 15 generative AI products. It spends $2 billion (£1.5 billion) a year on technology and employs more than 12,000 “technologists”, of which about half are software engineers.
RELX’s LexisNexis Legal & Professional arm has been a major beneficiary of the rapid adoption of its analytics and generative AI products, which are built and trained on one of the world’s largest repositories of accurate and exclusive legal content.
Its revenue growth accelerated from 1% in 2020 to today’s third-quarter rate of 10%, turning Legal from RELX’s slowest-growing business to its fastest-growing operation.
The other parts of RELX are its Risk and Business Analytics division and the Elsevier journals operation Science, Technical and Medical (STM). They recorded revenue growth of 8% and 6% respectively in today’s update, while the Exhibitions arm posted 4%.
- A big upgrade for BP earnings and price target
- Mixed bag for Barclays as key division triggers profit miss
- Sainsbury’s upgrades guidance but faces headwinds
RELX said: “We continue to see positive momentum across the group, and we expect another year of strong underlying growth in revenue and adjusted operating profit, as well as strong growth in adjusted earnings per share on a constant currency basis.”
Bank of America recently backed the shares with an unchanged price target of 4,000p as it turned its attention towards the company’s STM investor seminar on 3 November.
It expects the division’s growth rate to accelerate to 8% by 2029, driven by an improved market backdrop in academic publishing as AI accelerates research output and enhances the value of verifiable content/data.
The bank also highlighted the scale-up potential of LeapSpace, RELX’s AI workflow tool for researchers.
Sage Group (The) (LSE:SGE), which is the largest Finsbury holding, is another stock whose recent performance has countered fears about incumbent, business-critical software companies.
Train said in September’s Finsbury factsheet: “The pick-ups in RELX’s and Sage’s growth rate are markers that support our proposition that incumbents and, most importantly, proprietary data owners, are better positioned to win from AI than their share prices currently suggest.”
Meanwhile, London Stock Exchange continues to see encouraging take-up of its Model Context Protocol (MCP) service that supplies LSEG’s data in an AI-friendly format.
Over two-thirds of LSEG’s top 50 data and analytics customers have now connected to MCP servers, while consumption through this channel for all users has grown fivefold quarter-on-quarter.
- Wild’s Winter Portfolios 2026-27: seeking a 10th year of profits
- US midterms 2026: what election could mean for your portfolio
- Find out the latest UK Budget news here
The company is on track to deliver its strongest annual growth since 2018 after raising its revenues guidance to at least 8%, from the 7%-7.5% previously forecast. It also upgraded guidance for margin expansion and free cash flow.
The strong cash generation has enabled LSEG to announce the $3.5 billion acquisition of New York-based Octus, a deal that adds solutions in the high-growth illiquid and private credit space.
Alongside the planned acquisition of Trumid credit trading services, the deal is expected to boost LSEG’s position as a global leader in fixed-income data and trading.
Buybacks and dividends also mean LSEG is on track to return 10% of its market capitalisation to shareholders between January and February 2027, with capacity for a further £1 billion-£1.5 billion of buybacks in 2027.
UBS said: “Strategically, we think the deal makes sense. More importantly, after defending its business model against AI over the past 15 months, we think LSEG’s move to an offensive posture could be a positive for shares.”
The bank, which has a price target of 11,700p, recently noted that LSEG’s 15 times forward price/earnings multiple was the company’s lowest valuation in more than 12 years.
Train said recently: “A modest improvement in perception of the durability of LSEG’s financial data assets could bring a very marked share price gain, we believe.”
The outlook for LSEG, Relx and other AI-exposed stocks is likely to be among the topics when Train answers questions from ii Community members in an interview planned for next week.
- eyeQ: time to sell this AI beneficiary?
- Sign up to our free newsletter for investment ideas, latest news and award-winning analysis
- Stockwatch: the share poised to benefit from a new political alliance
In today’s session, LSEG shares were beaten to the top of the FTSE 100 risers board by Rentokil Initial (LSE:RTO) after the pest control business published a reassuring third-quarter update.
The rise of 25.6p to 340.3p was in sharp contrast to the reaction to July’s interim results, when new boss Mike Duffy retired a key North America margin target of 20% in order to prioritise volume growth and investment over short-term margin expansion.
The need to focus on the top line was highlighted by second-quarter revenues growth in North America pest control of 2.4%, a slowdown from 2.8% in the first quarter amid some weakness in residential lead flow towards the end of the period and into July.
Today’s third-quarter figure of 2.4% contributed to “solid” overall revenues growth of 3.4% as Rentokil said it expected to meet the City’s profit expectations for the year. The shares remain 23% lower this year, having dipped below 300p at the end of September.
Duffy, who announced a £200 million share buyback, added today: “We have a great business and a clear vision of how to improve performance. This, combined with our focus on efficiency and a disciplined approach to capital allocation, will enable us to create a stronger Rentokil.”
These articles are provided for information purposes only. Occasionally, an opinion about whether to buy or sell a specific investment may be provided by third parties. The content is not intended to be a personal recommendation to buy or sell any financial instrument or product, or to adopt any investment strategy as it is not provided based on an assessment of your investing knowledge and experience, your financial situation or your investment objectives. The value of your investments, and the income derived from them, may go down as well as up. You may not get back all the money that you invest. The investments referred to in this article may not be suitable for all investors, and if in doubt, an investor should seek advice from a qualified investment adviser.
Full performance can be found on the company or index summary page on the interactive investor website. Simply click on the company's or index name highlighted in the article.