Shares for the future: promotion creates new top 10 stock
Previously a mid-table share, this company races up the table after analyst Richard Beddard increased its score. Here’s why.
20th November 2026 15:07
by Richard Beddard from interactive investor
Volution’s growth is impressive, but a recent acceleration in acquisitions may be followed by a slowdown. That would be a good thing.
Volution: not just fresh air
Volution Group (LSE:FAN) manufactures ventilation systems for our homes, principally, but increasingly for large buildings like schools, hospitals, offices, car parks, data centres and mines.
Chief executive Ronnie George has run Volution since 2012. Prior to that he was managing director of its market-leading UK subsidiary, Vent-Axia.
- Invest with ii: SIPP Account | Stocks & Shares ISA | See all Investment Accounts
He has overseen the international expansion of Volution, which was a UK operation in 2012. Today, it owns 30 brands in 17 countries. Three regions contribute roughly a third of revenue each: the UK, Continental Europe, and Australasia.
Volution’s transformation is the result of acquisitions, a roll-up strategy that extended into Europe, starting in 2015, and Australasia, starting in 2018.
Scale allows Volution to operate more efficiently, principally by sharing know-how, cross-selling products, strengthening distribution, supplying more content to large projects, and collectively sourcing the thousands of raw materials and components it needs to assemble ventilation products.
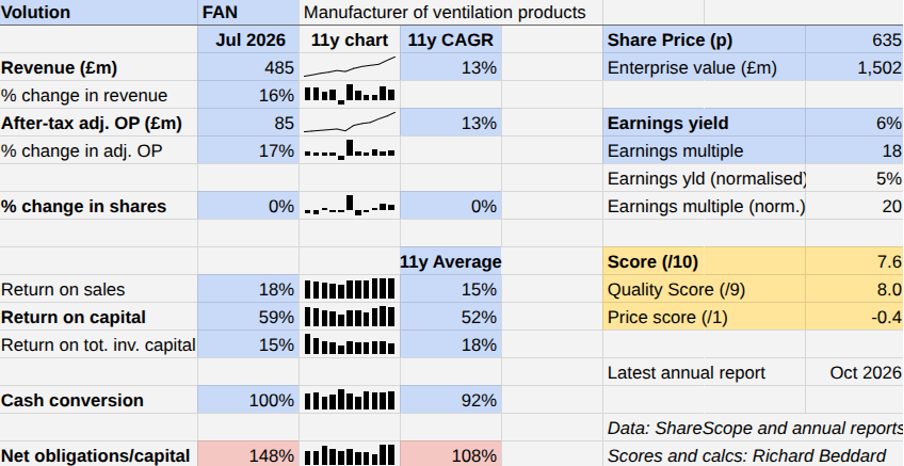
In theory, the bigger Volution gets, the more competitive it is, and Volution is a lot bigger than it used to be. The company has grown revenue and profit at a compound annual growth rate (CAGR) of 13%, while delivering consistently high return on capital and cash conversion.
I believe the roll-up has been smooth and profitable because of Volution’s culture. Since 2012, it has trained senior managers in the principles that underpin its performance. They are not revolutionary principles, but their consistent application may be unusual.
Now, it is extending leadership training to people lower down the corporate hierarchy. Volution reports a high level of staff engagement, and beyond making money it has a purpose: “Healthy air, sustainably”.
That is a banner I can get behind. High energy costs, climate change, and the health consequences of poor ventilation mean demand for efficient ventilation systems should remain strong, partly driven by regulation.
Roll-up speeds up
For most of the last decade, Volution’s growth has come from a succession of piecemeal acquisitions. The pace changed with the acquisition of Fantech, its largest ever, in December 2024.
Fantech was followed by ACI in February 2026. Even though ACI only contributed six months of revenue to Volution in the year to July 2026, these two acquisitions tripled the revenue contribution of Australasia, lifting it close to parity with the UK and Continental Europe.
As a result of the spending, debt (including leases) increased to 148% of operating capital at the year end, which is high by Volution’s historically high standard. Just after the year end, it added to the debt by acquiring getAir, a smaller business based in Germany.
- Stockwatch: what next for Nvidia minus its founder CEO
- Stockwatch: this FTSE 250 share remains on my buy list
I doubt this debt puts Volution’s finances at great risk. The business is primarily an assembler, and debt looks big compared to capital because it only requires modest amounts of capital to operate.
Comparing the debt to cash flow is somewhat more reassuring. If Volution gave up on acquisitions for a while and traded as well as it has in the past, it could probably repay the debt in three years from free cash flow.
However, I think more debt would be problematic. In August, after the acquisition of getAIR, debt excluding leases was 1.8 times EBITDA, close to the edge of Volution’s self-imposed comfort limit of 2 times EBITDA at the point of an acquisition’s completion.
I expect, and hope for, a return to the gradualism that has served the company well. That being the case, Volution must rely more heavily on organic growth to reach its target of 10% annual revenue growth. Organic growth has been impressively consistent (excluding the pandemic year of 2020), but also quite modest.
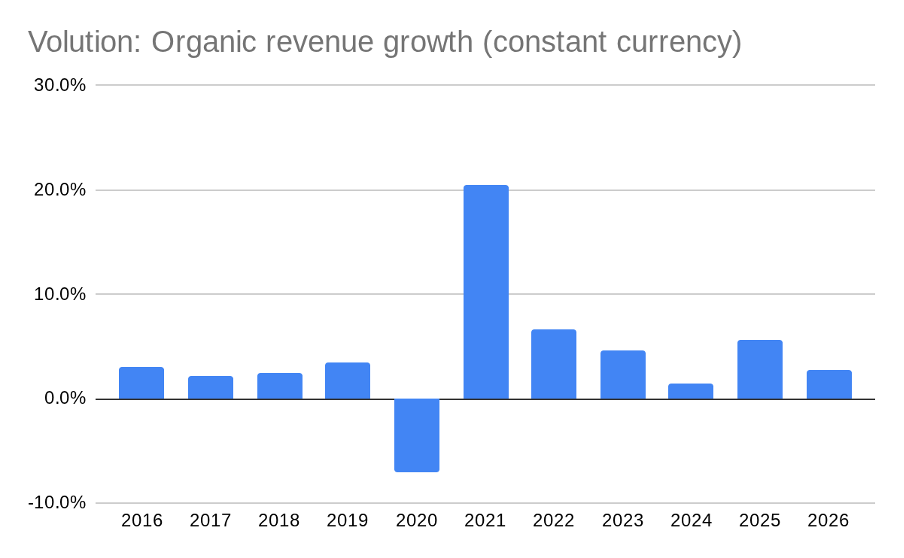
In 2026, Volution grew organic revenue 2.8% (adjusting for currency movements), below its 4.2% 10-year average. This was mostly due to flat revenue in the UK.
The biggest detractor was the UK commercial market, where Volution is a challenger. Revenue fell 10% and contributed 15% of the UK total. The company says the market was weak, but its performance was weaker and it is investing in product and sales capabilities to increase market share.
- Where to find the best investment returns in 2027
- Sign up to our free newsletter for investment ideas, latest news and award-winning analysis
The UK residential market, where Volution is market leader, is also challenged by a slump in new builds, which brought in about 45% of UK residential revenue in 2026. The rest comes from maintenance and improvement, which is less cyclical.
Organic growth was stronger in Continental Europe and Australasia, and Volution has higher expectations for these markets in 2027.
Nevertheless, the aggregate of seven brokers is for sub-par revenue growth of 9% in 2027. Those estimates will include a full-year contribution from ACI and a maiden contribution from getAir.
Scoring Volution: still a fan
Out of an abundance of caution, I have penalised Volution for its increased complexity. ACI supplies ducting to the mining industry in Australia and internationally, which seems a far cry from domestic and most commercial ventilation systems.
Perhaps sensing this fear, Ronnie George responded to a question about the diversity of recent acquisitions in a mock Q&A in the annual report. He is “...excited that, as we continue to grow, the range and ‘pipeline’ of opportunities that make sense to us is also expanding”.
Given Volution’s record, I am inclined to trust his judgement, but the combination of debt and complexity makes me a little circumspect.
| Volution | FAN | Manufacturer of ventilation products | 19/11/2026 | 7.6/10 |
| How capably has Volution made money? | 3.0 | |||
| Under chief executive Ronnie George, Volution has grown revenue and profit at 13% CAGR since it floated in 2014. Most of this growth has been acquisitive. Volution’s subsidiary brands are highly profitable and cash generative, which is probably a result of its scale and stable culture. | ||||
| How big are the risks? | 2.5 | |||
| The acquisition of Fantech in November 2024 and ACI in December 2025 raised debt to substantially more than operating capital, although prodigious cash flow makes it look affordable. A Chinese supply chain and cyclical markets could dent profitability, but so far Volution has prospered consistently. | ||||
| How fair and coherent is its strategy? | 2.5 | |||
| Volution is scaling up to become more efficient. A high ROTIC indicates it is efficient, and has not overpaid for acquisitions. Diversification may improve resilience but also makes it more complex. Ventilation products improve air quality in buildings and the health of occupants and the environment. | ||||
| How low (high) is the share price compared to normalised profit? | -0.4 | |||
| High. A share price of 635p values the enterprise at £1,502 million, about 20 times normalised profit. | ||||
| NB: Bold text indicates factors that reduce the score. Bold and italicised text doubly so. The maximum score is 3 for each criterion except price, which has a maximum of 1 (explained here) | ||||
| Previous score (February 2026): 6.8 | ||||
Overall, Volution’s score has improved since I last scored it in February. The modest decline in the quality element of its score has been trumped by a larger increase in its price score.
31 Shares for the future
Here is the ranked list of Decision Engine shares. I review the scores at least once a year, soon after each company has published its annual report. The price scores are calculated using the share price prior to publication.
Generally, I consider shares that score more than 5 out of 10 to be worthy of long-term investment in sizes determined by the ideal holding size (ihs%).
Tristel (LSE:TSTL), Softcat (LSE:SCT) and YouGov (LSE:YOU) have published annual reports and are due to be re-scored.
| company | description | score | qual | price | ih% | |
| 1 | FW Thorpe | Makes lighting systems for commercial, industrial and public settings | 9.4 | 8.5 | 0.9 | 8.9% |
| 2 | Hollywood Bowl | Operates tenpin bowling centres | 8.3 | 8.0 | 0.3 | 6.6% |
| 3 | James Latham | Distributes imported panel products, timber, and laminates | 8.0 | 7.0 | 1.0 | 6.0% |
| 4 | Solid State | Manufactures electronic systems and distributes components | 7.9 | 7.0 | 0.9 | 5.8% |
| 5 | Cake Box | Cake shop (Cake Box) and sweet shop (Ambala) franchisor | 7.9 | 7.0 | 0.9 | 5.7% |
| 6 | Porvair | Manufactures filters and laboratory equipment | 7.7 | 8.0 | -0.3 | 5.4% |
| 7 | Howden Joinery | Supplies kitchens and joinery to builders and online to DIYers | 7.7 | 7.0 | 0.7 | 5.4% |
| 8 | Volution | Manufacturer of ventilation products | 7.6 | 8.0 | -0.4 | 5.2% |
| 9 | Anpario | Manufactures natural animal feed additives | 7.5 | 7.0 | 0.5 | 5.1% |
| 10 | Oxford Instruments | Makes imaging and semiconductor manufacturing systems | 7.5 | 7.0 | 0.5 | 5.0% |
| 11 | Renew | Maintains and improves road, rail, water, and energy infrastructure | 7.5 | 7.5 | 0.0 | 5.0% |
| 12 | Games Workshop | Designs, makes and distributes Warhammer. Licences IP | 7.4 | 9.0 | -1.6 | 4.7% |
| 13 | Quartix | Supplies vehicle tracking systems to small fleets | 7.4 | 7.0 | 0.4 | 4.7% |
| 14 | Bunzl | Distributes essential everyday items consumed by businesses | 7.2 | 7.0 | 0.2 | 4.4% |
| 15 | Churchill China | Manufactures tableware for restaurants etc. | 7.0 | 6.0 | 1.0 | 4.0% |
| 16 | Jet2 | Flies people to holiday locations, often on package tours | 7.0 | 6.0 | 1.0 | 4.0% |
| 17 | Judges Scientific | Acquires and grows businesses that manufacture scientific instruments | 7.0 | 6.0 | 1.0 | 4.0% |
| 18 | Bloomsbury Publishing | Publishes books and educational resources | 6.9 | 7.5 | -0.6 | 3.8% |
| 19 | Auto Trader | Online marketplace for motor vehicles | 6.9 | 6.0 | 0.9 | 3.8% |
| 20 | YouGov | Surveys public opinion and conducts market research online | 6.9 | 6.0 | 0.9 | 3.7% |
| 21 | Cohort | Manufactures/supplies defence tech, training, consultancy | 6.7 | 7.5 | -0.8 | 3.3% |
| 22 | Macfarlane | Distributes and manufactures protective packaging | 6.5 | 5.5 | 1.0 | 3.0% |
| 23 | Softcat | Sells software and hardware to businesses and public sector | 6.2 | 6.5 | -0.3 | 2.5% |
| 24 | Advanced Medical Solutions | Manufactures surgical adhesives, sutures and dressings | 6.2 | 6.5 | -0.3 | 2.5% |
| 25 | Tristel | Manufactures hospital disinfectant | 6.0 | 8.0 | -2.0 | 2.5% |
| 26 | Focusrite | Designs recording equipment, synthesisers and sound systems | 6.0 | 5.0 | 1.0 | 2.5% |
| 27 | Keystone Law | Operates a network of self-employed lawyers | 5.8 | 7.0 | -1.2 | 2.5% |
| 28 | 4Imprint | Customises and distributes promotional goods | 5.7 | 8.0 | -2.3 | 2.5% |
| 29 | Renishaw | Makes manufacturing automation tools and 3D printers | 5.6 | 7.0 | -1.4 | 2.5% |
| 30 | Goodwin | Casts and machines steel and processes minerals for niche markets | 5.3 | 6.0 | -0.7 | 2.5% |
Click on a share's score to see a breakdown (scores may have changed due to movements in share price). Key: qual is the share’s score out of 9 for the three quality factors (capabilities, risks, and strategy), price is the price score from -3 to +1, and ih% is the suggested ideal holding size as a percentage of the total value of a diversified portfolio.
Richard Beddard is a freelance contributor and not a direct employee of interactive investor.
Richard owns Volution and many shares in the Decision Engine. He weights his portfolio so it owns bigger holdings in the higher-scoring shares.
For more on the Decision Engine and Share Sleuth, please see Richard’s explainer.
Contact Richard Beddard by email: richard@beddard.net or on Twitter: @RichardBeddard
These articles are provided for information purposes only. Occasionally, an opinion about whether to buy or sell a specific investment may be provided by third parties. The content is not intended to be a personal recommendation to buy or sell any financial instrument or product, or to adopt any investment strategy as it is not provided based on an assessment of your investing knowledge and experience, your financial situation or your investment objectives. The value of your investments, and the income derived from them, may go down as well as up. You may not get back all the money that you invest. The investments referred to in this article may not be suitable for all investors, and if in doubt, an investor should seek advice from a qualified investment adviser.
Full performance can be found on the company or index summary page on the interactive investor website. Simply click on the company's or index name highlighted in the article.
Disclosure
We use a combination of fundamental and technical analysis in forming our view as to the valuation and prospects of an investment. Where relevant we have set out those particular matters we think are important in the above article, but further detail can be found here.
Please note that our article on this investment should not be considered to be a regular publication.
Details of all recommendations issued by ii during the previous 12-month period can be found here.
ii adheres to a strict code of conduct. Contributors may hold shares or have other interests in companies included in these portfolios, which could create a conflict of interests. Contributors intending to write about any financial instruments in which they have an interest are required to disclose such interest to ii and in the article itself. ii will at all times consider whether such interest impairs the objectivity of the recommendation.
In addition, individuals involved in the production of investment articles are subject to a personal account dealing restriction, which prevents them from placing a transaction in the specified instrument(s) for a period before and for five working days after such publication. This is to avoid personal interests conflicting with the interests of the recipients of those investment articles.